You worked hard to get your wealth into super. Keep the tax haven going after you die.
Superannuation is a tax haven with strict entry rules. It takes years to build your retirement savings. Before you die, plan how your spouse receives your pension and keeps eligible benefits in the superannuation environment.
Legal Consolidated’s SMSF Reversionary Pension Kit brings your Deed, pension instructions and trustee decisions together. Your accountant and financial planner work with a complete set of documents to put your pension arrangements into effect.
What is an SMSF reversionary pension?
You receive a pension from your SMSF. You nominate an eligible person, usually your spouse, to receive that pension after your death. With valid reversionary arrangements, your spouse’s entitlement starts automatically when you die.
Consider a husband and wife who rely on their SMSF pensions. The husband dies. His wife still needs income for the household. A properly established reversionary pension continues to her under its terms. The trustee administers that entitlement rather than choosing a new recipient for that pension.
The ATO explains this continuity in Taxation Ruling TR 2013/5. The governing rules and pension terms must give the beneficiary an automatic entitlement. Writing a name on a form does not fix inconsistent pension rules.
Keep eligible death benefits in super
A reversionary pension gives you a planned path for pension continuity. Another death benefit pension may also keep eligible benefits in super. The difference is that a valid reversionary pension establishes who receives the continuing pension before you die.
Money paid out of super is not always easy to put back. Contribution rules and caps restrict what your spouse contributes. Plan the pension, your spouse’s own super and the transfer balance cap together. The aim is to preserve available tax concessions and provide retirement income.
Death benefits must follow the cashing rules in reg 6.21 of the Superannuation Industry (Supervision) Regulations 1994 (Cth). A pension is available only to an eligible recipient. The Kit supplies the legal documents; your financial planner and accountant advise on the amounts and strategy for your circumstances.
Your SMSF Deed, nomination and trustee acceptance must work together
Your Deed sets the fund’s rules. Your pension documents record the pension terms. Your nomination identifies its intended recipient. The trustee’s acceptance records the decision. Each document has a job.
Legal Consolidated includes a Deed of Variation and adoption minutes with the Kit. You also receive the Member Nomination Instruction and Binding Trustee Resolution. These documents establish a consistent framework for your pension arrangements, subject to the existing Deed’s amendment power and required consents.
Already receiving a pension? Check its terms before making a change. The Kit does not rewrite the history of an existing pension or cure an invalid earlier document. Your advisers decide whether to amend an existing arrangement or commence a new pension.
John’s pension records were missing. His trustee went to court.
John Giles had a substantial pension. After his death, the fund could not locate the original documents establishing the pension and its reversionary terms. His trustee asked the Supreme Court of Queensland to determine the position.
In Re Narumon Pty Ltd[2018] QSC 185, the Court examined the evidence and confirmed his wife’s reversionary entitlement. The case shows why pension records matter long after the day you sign them.
Your Legal Consolidated Kit supplies the instructions, resolutions and pension records in one suite. Complete the documents that apply to your arrangements. Sign them and keep them together. Give your accountant a clear record of what the member requested and what the trustee accepted.
Does a reversionary pension override a binding death benefit nomination?
The fund’s governing rules and the pension terms determine priority. You need those documents to agree before a death creates competing claims.
Under this Kit’s Deed, a valid reversionary pension nomination accepted by the trustee takes priority over a conflicting binding death benefit nomination or other death benefit agreement for that specific pension account. It does not dispose of every other benefit in the fund.
In Hill v Zuda Pty Ltd[2022] HCA 21, the High Court confirmed that regulation 6.17A does not apply to SMSFs. The judgment does not give every reversionary nomination priority over every death benefit nomination. Your Deed must establish the rules.
Review your pension nomination alongside your binding death benefit nomination and estate planning. Deal with each pension account and the remaining benefits.
What happens to your spouse’s transfer balance cap?
Your spouse may already have a retirement phase pension. An inherited pension must fit into the transfer balance rules as well.
For a qualifying reversionary retirement phase pension, the transfer balance credit arises 12 months after death. Its amount is based on the pension’s value at death. This gives your spouse time to plan how to manage their cap. It does not postpone their entitlement to the pension.
The rule is in s 294-25 of the Income Tax Assessment Act 1997 (Cth). Your accountant must also attend to the applicable reporting deadlines. The 12-month delay in the credit is not a 12-month holiday from reporting.
Your spouse’s existing pensions, personal cap and proposed commutations all matter. Ask your accountant and financial planner to run the figures while you are both alive.
The complete SMSF Reversionary Pension Kit
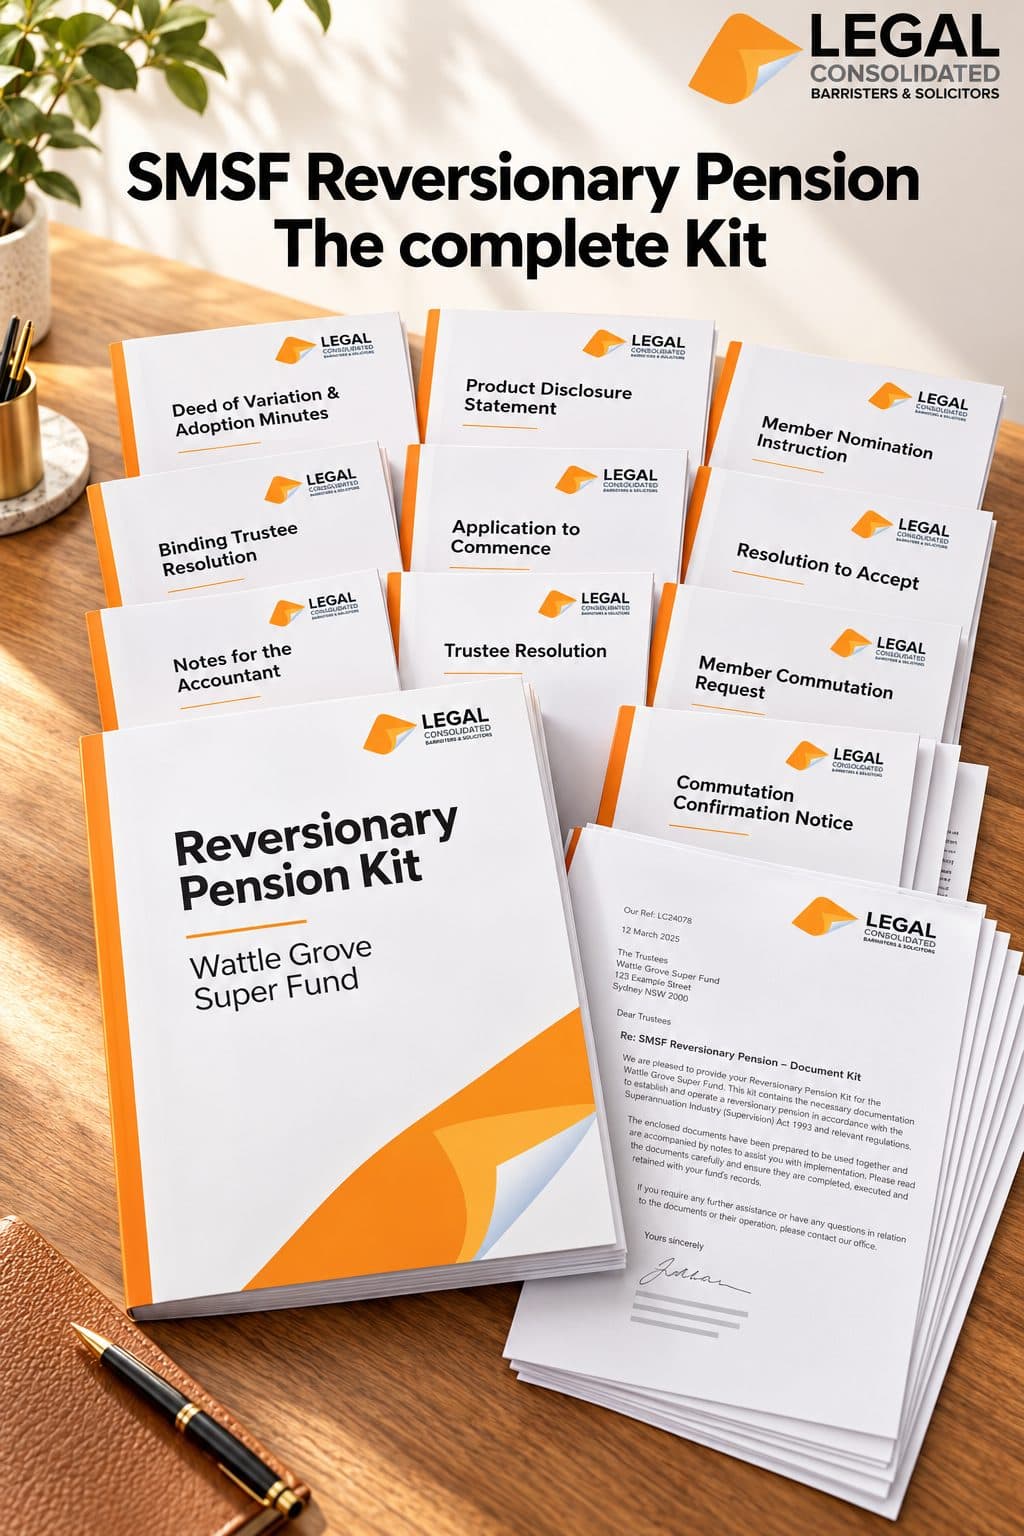
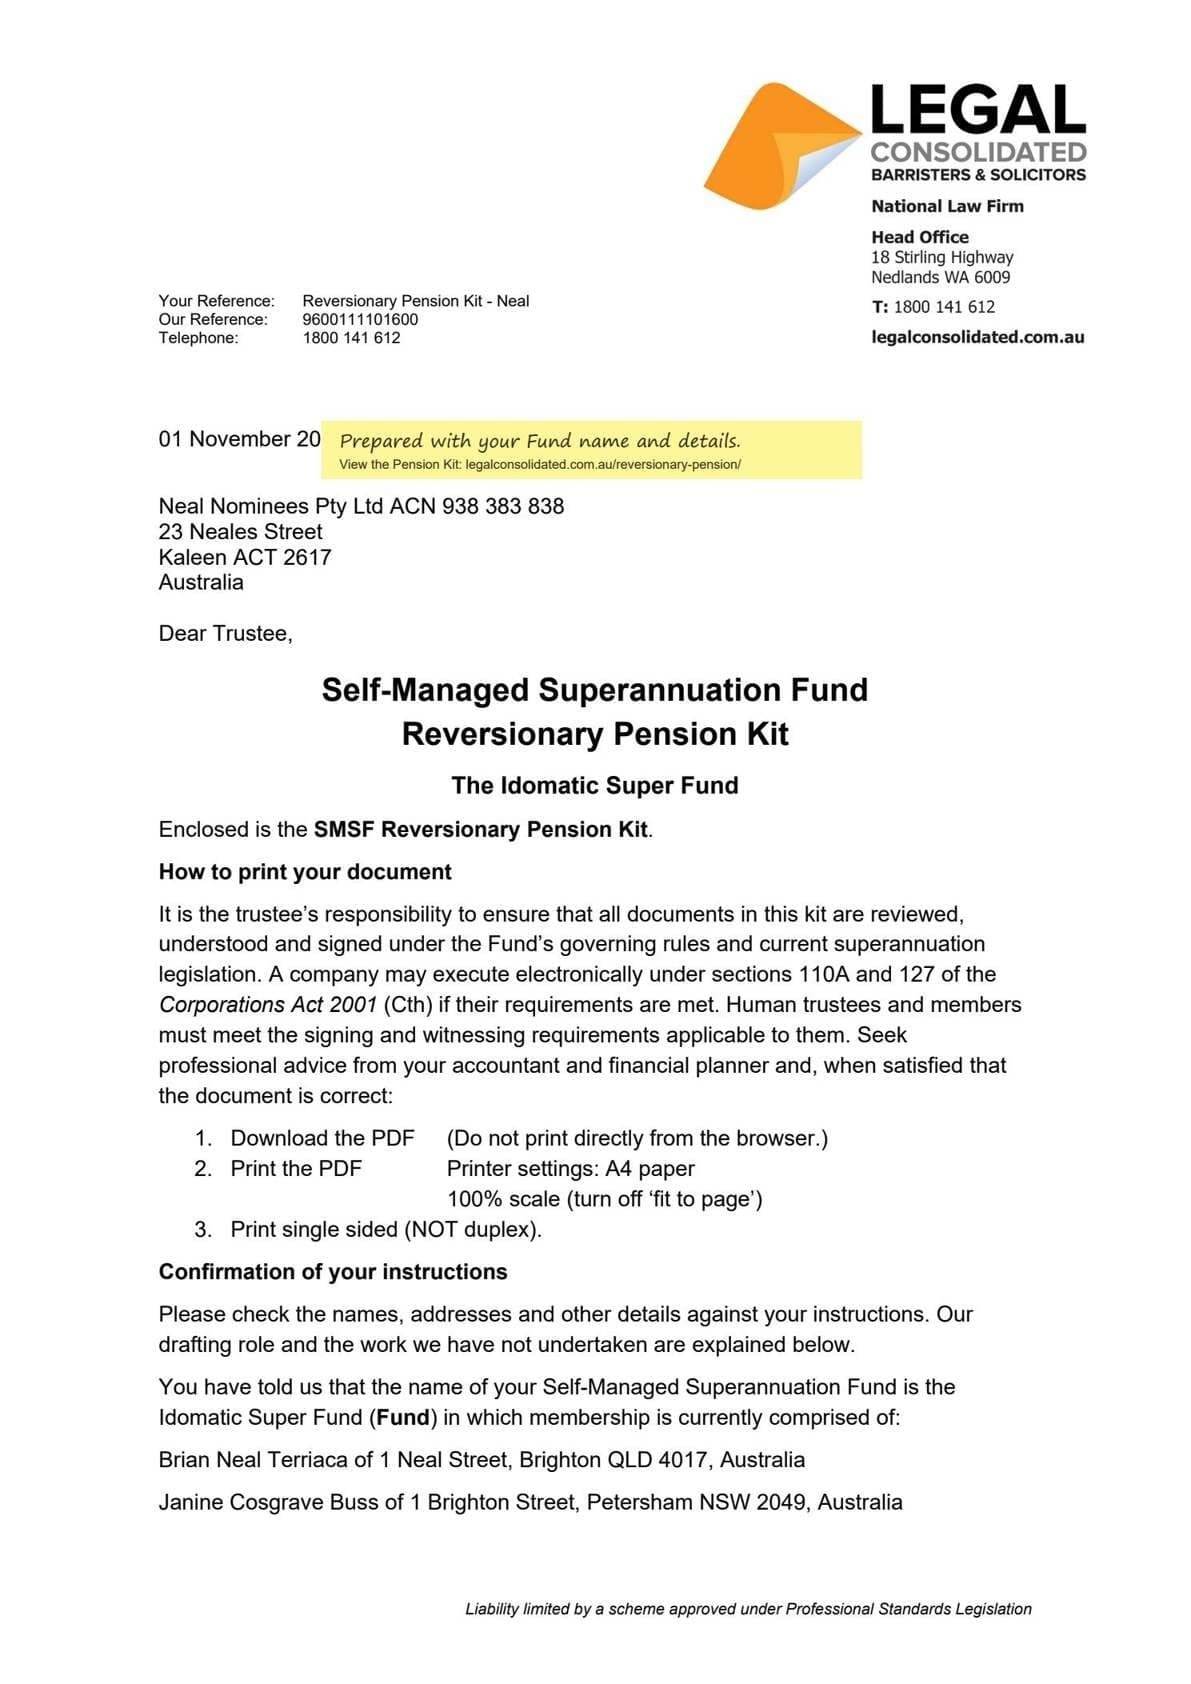
You receive our law firm’s cover letter and instructions, together with the documents for establishing, accepting and recording your pension arrangements. The Kit includes the standalone Product Disclosure Statement.
Deed of Variation and adoption minutes — establish the pension framework in your SMSF’s governing rules.
Product Disclosure Statement — explain the fund’s risks, rights and responsibilities to members.
Member Nomination Instruction and Binding Trustee Resolution — record the member’s instructions and the trustee’s acceptance.
Application to Commence — record the request to start the pension.
Resolution to Accept — document acceptance of the application.
Notes for the Accountant — guide the preparation of pension commencement and commutation records.
Trustee Resolution — provide a structure for recording the pension commencement decision.
Member Commutation Request — record a request to commute all or part of a pension.
Commutation Confirmation Notice — confirm the commutation for the fund’s records.
The commencement and commutation examples give your accountant and financial planner a practical starting point. They tailor the relevant documents to the fund’s pension, tax and reporting arrangements.
Your pension arrangements change as you retire, inherit a pension or manage your transfer balance cap. A commutation converts all or part of a pension into a lump sum entitlement. It is different from drawing an ordinary pension payment.
A qualifying commutation creates a transfer balance debit under s 294-80 of the Income Tax Assessment Act 1997 (Cth). Ordinary pension payments do not create that debit. Your accountant needs records showing which transaction occurred.
A commuted death benefit pension must not move into accumulation. Death benefit cashing rules continue to apply. The Kit’s request and confirmation documents help your advisers record the intended transaction and its completion.
Does the Kit cover account based pensions and transition to retirement?
The Kit includes documents for account based pensions and transition to retirement income streams. Your advisers select the appropriate pension and complete its details. Transition to retirement pensions have different payment and tax rules until the relevant retirement phase requirements are met.
Your accountant also checks pension payments, reporting and any proposed pension restart. A pension refresh requires deliberate steps and records. Simply changing the name of an existing pension does not create a new one.
Who receives your reversionary pension?
Your spouse is a common choice. The recipient must satisfy the death benefit pension eligibility rules when you die. An adult child does not qualify merely because you name them.
For a child, the rules distinguish children under 18, children under 25 who were financially dependent on you, and children with a qualifying disability. A child’s pension usually must be cashed as a lump sum by age 25 unless the disability exception applies. Your advisers should check the tests in reg 6.21(2A)–(2B) against the proposed beneficiary’s circumstances.
What if your spouse dies before you?
Review your pension nomination. Check who receives the remaining benefits under your fund’s rules and other death benefit arrangements. Marriage, separation and a beneficiary’s death are reasons to revisit the documents.
Your pension beneficiary and the person who controls the trustee company perform different roles. Review the company’s control arrangements as part of the same planning. Our SMSF corporate trustee power of attorney page explains another part of that discussion.
Build your pension documents with a national law firm
More than 4,600 accountants, financial planners and lawyers use Legal Consolidated to build legal documents. Our lawyers prepare the Kit’s legal framework and instructions. You receive the finished documents with our law firm’s cover letter.
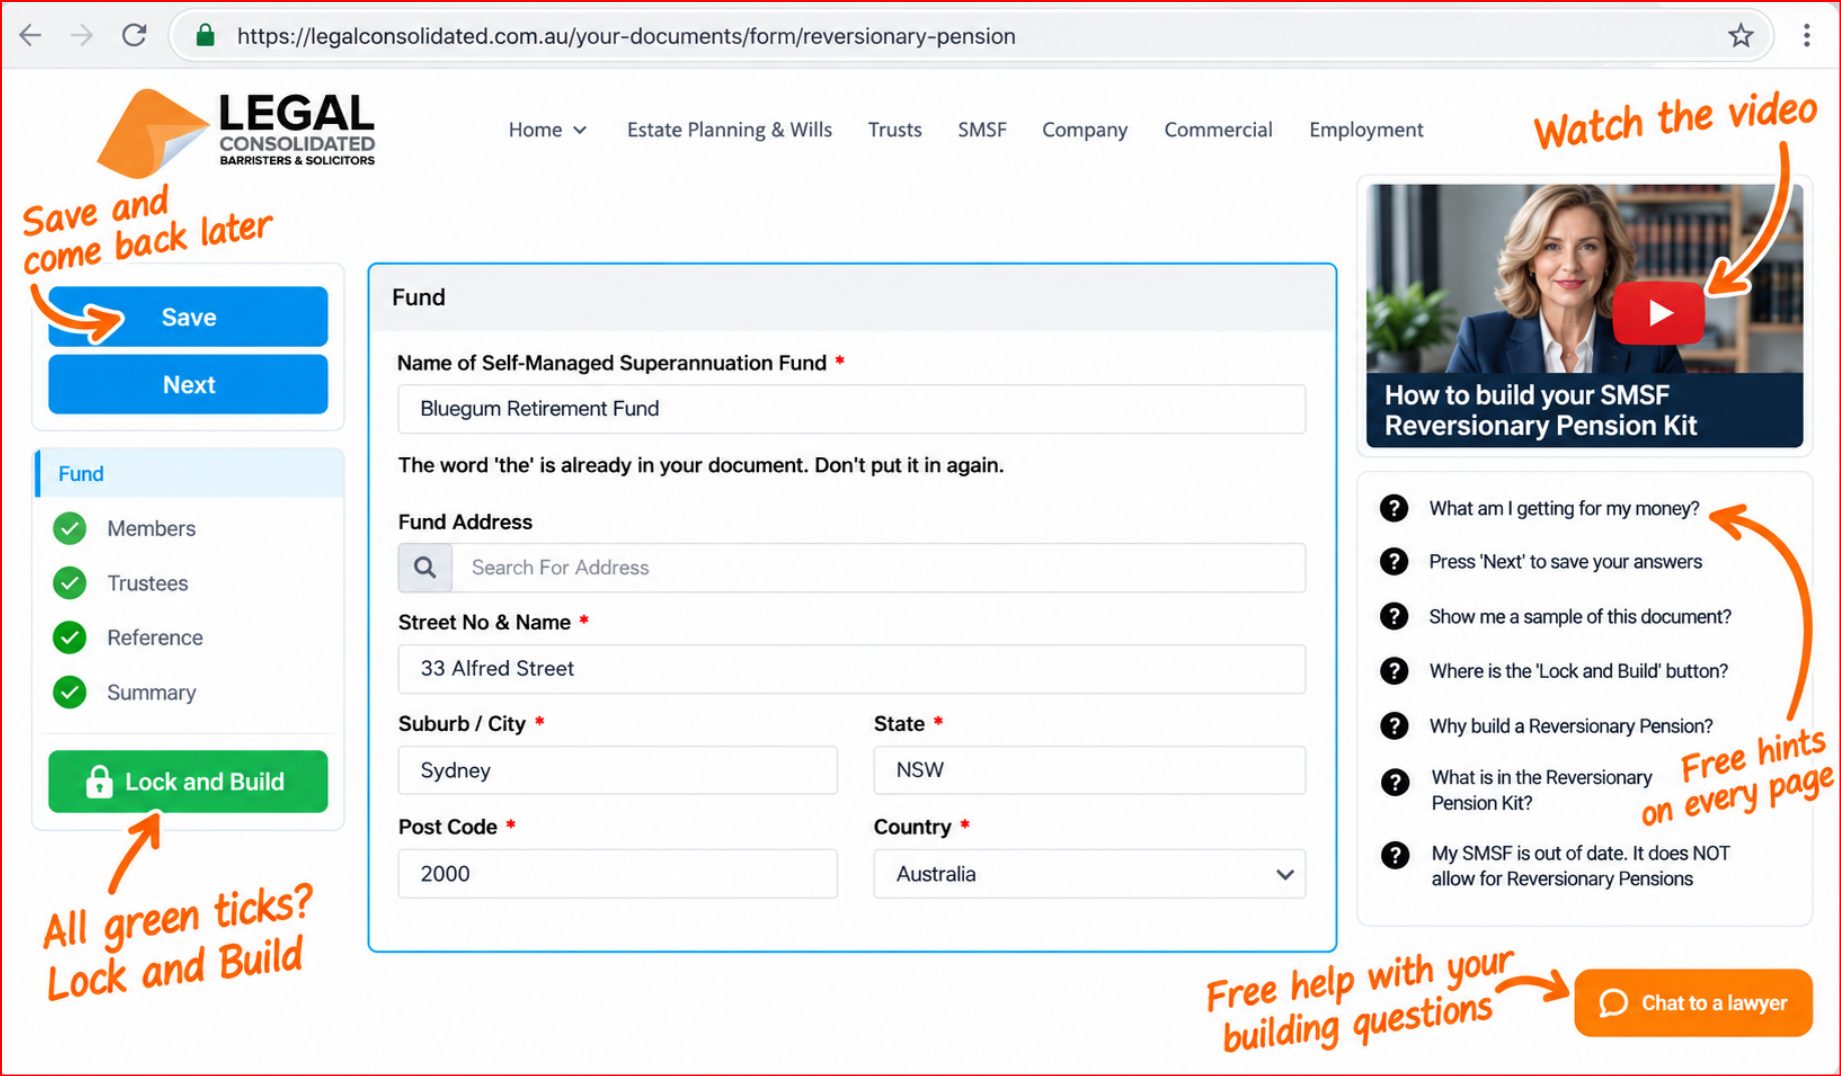
Start building for free. Read the hints as you answer the questions. Save your answers and return later. Contact us for help with the building questions. Your accountant and financial planner advise on pension amounts, investments, tax and the strategy that meets your needs.
Use the checklist to gather your information. Read the sample to see the complete suite. Then build the documents for your SMSF.