-
SMSF Deed
-
$446 includes GST
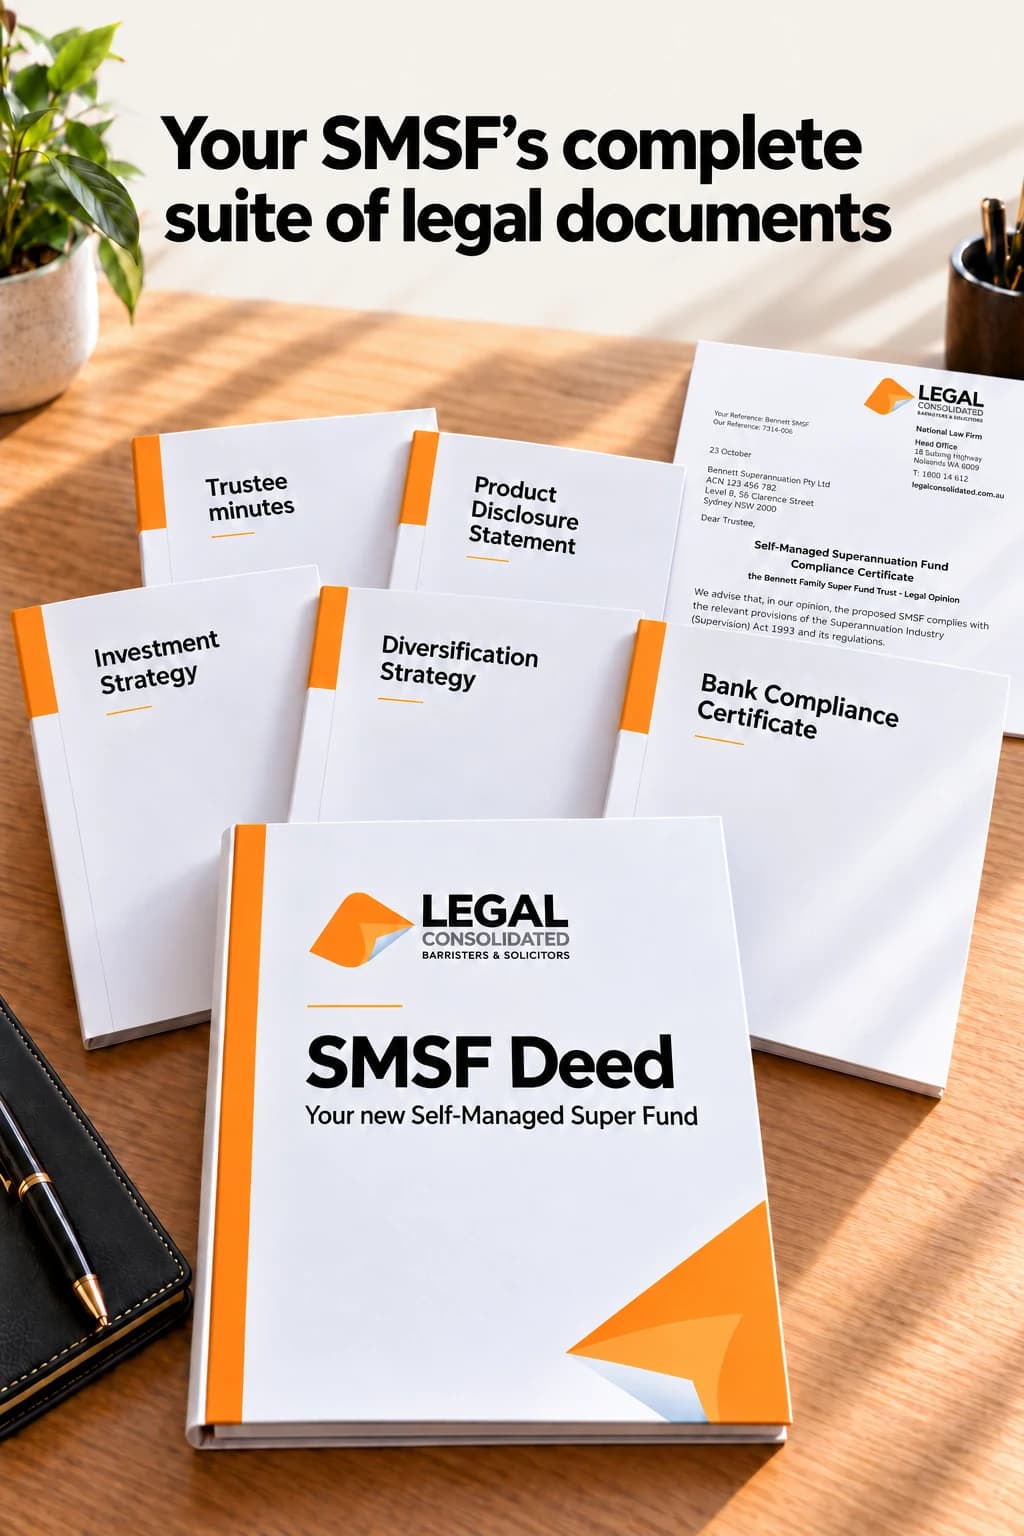
Seven SMSF legal documents to protect you
- SMSF Deed
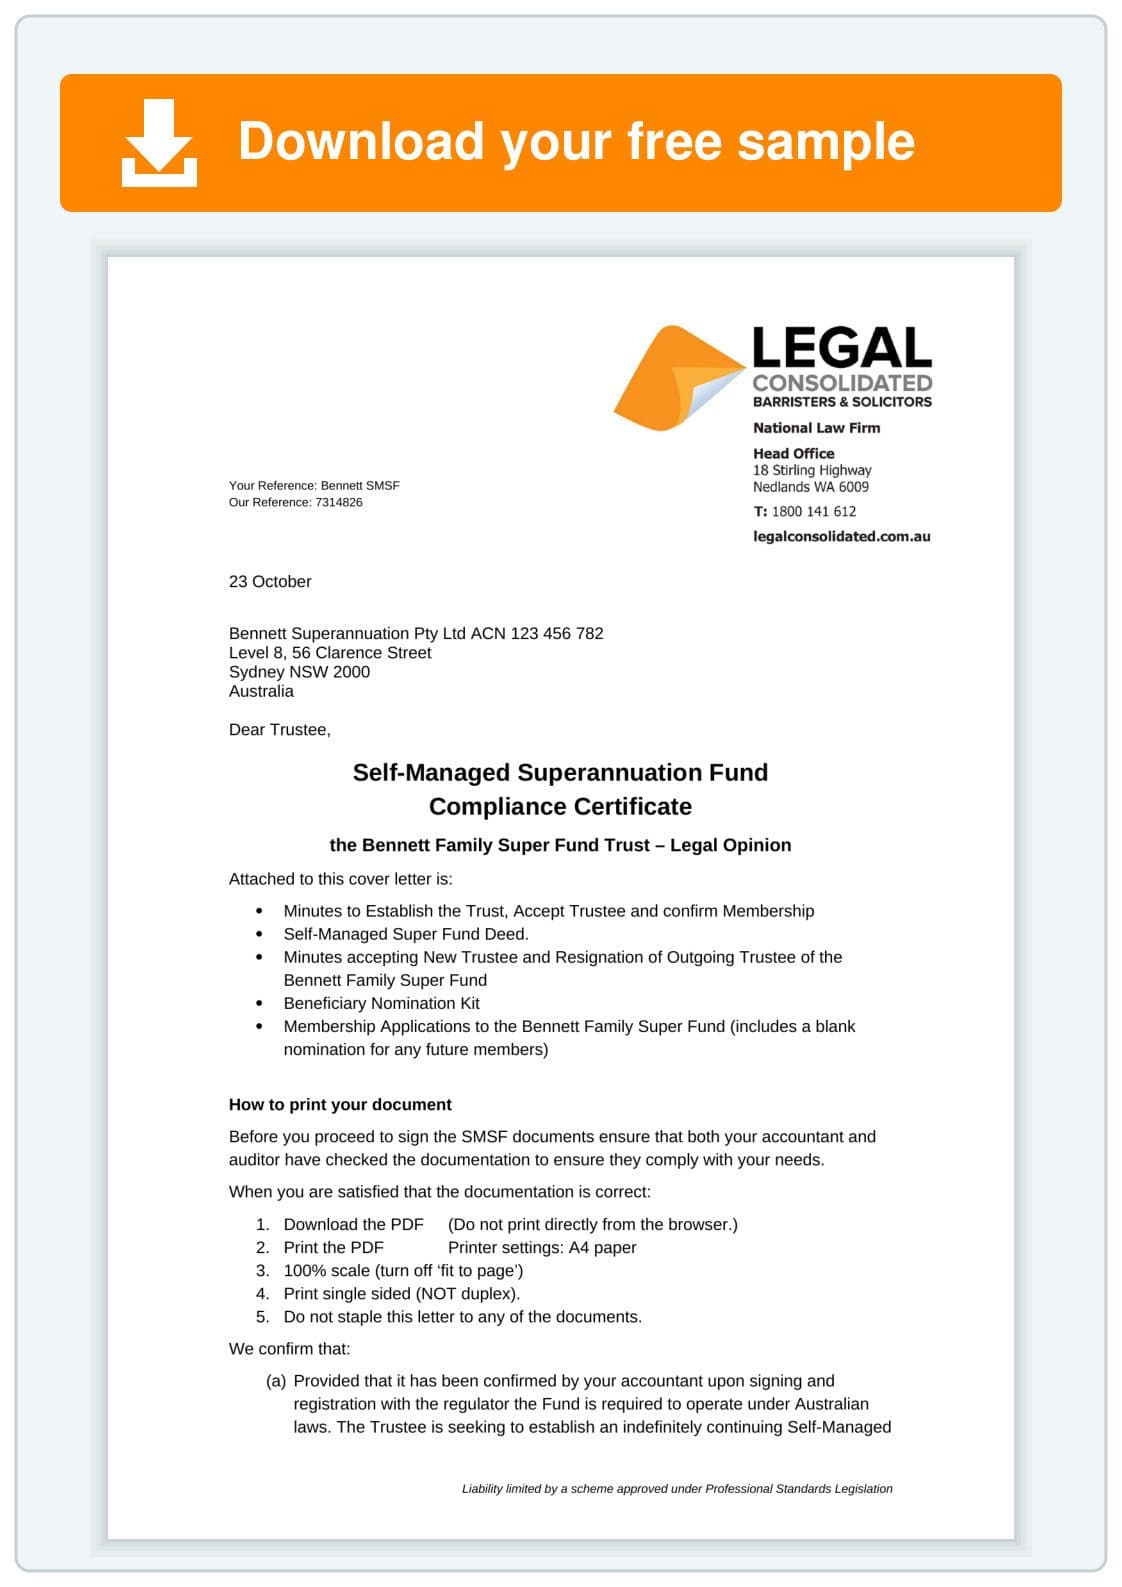
- Law firm cover letter
- Trustee minutes
- Product Disclosure Statement
- Investment Strategy
- Diversification Strategy
- Bank Compliance Certificate
Take true control of your superannuation. Your SMSF Deed is the legal engine of your fund, determining the exact powers available to your trustee. Those powers matter when you invest, borrow, draw a pension, or decide who receives your wealth at death. Build the financial strategy with your accountant and adviser; build the legal rules to enforce it with this suite of Legal Consolidated SMSF documents.
Already have an SMSF? Update your existing fund’s deed. This page is for establishing a new fund.
Legal Consolidated is a national specialist tax and superannuation law firm. We prepare your legal documents through our online building system.
Our law firm’s letter covers your documents and is addressed to the trustee client. The letter identifies our legal work and explains the signing and implementation steps. This keeps our legal drafting distinct from the accountant’s and financial planner’s professional work.
We do not resell another law firm’s template. We prepare your documents.
Professionals across Australia use Legal Consolidated to prepare legal documents for their clients.
Their experience gives us the questions that arise in practice: arguments raised in ATO audits, provisions questioned, and problems encountered when families separate, members lose capacity, or someone dies.
Our lawyers track tax and superannuation developments, bankruptcy cases, trust disputes, family law judgments and estate litigation. We draw on that knowledge in our drafting and the guidance you receive as you build.
Decide who receives your super and put binding instructions in place.
The deed provides for a separately signed death benefit agreement that binds the trustee and does not automatically expire after three years. It also provides alternative binding and non-binding nomination options.
The distinction matters. A non-binding nomination leaves the trustee with discretion. A valid binding agreement requires the trustee to follow its terms, subject to superannuation law.
The High Court confirmed in Hill v Zuda Pty Ltd [2022] HCA 21 that reg 6.17A does not apply to SMSFs. Your fund’s governing rules and the way you execute your direction therefore matter.
Signing the SMSF Deed alone does not complete your death benefit direction. Complete and sign the separate agreement, give it to the trustee and keep it with the fund’s records.
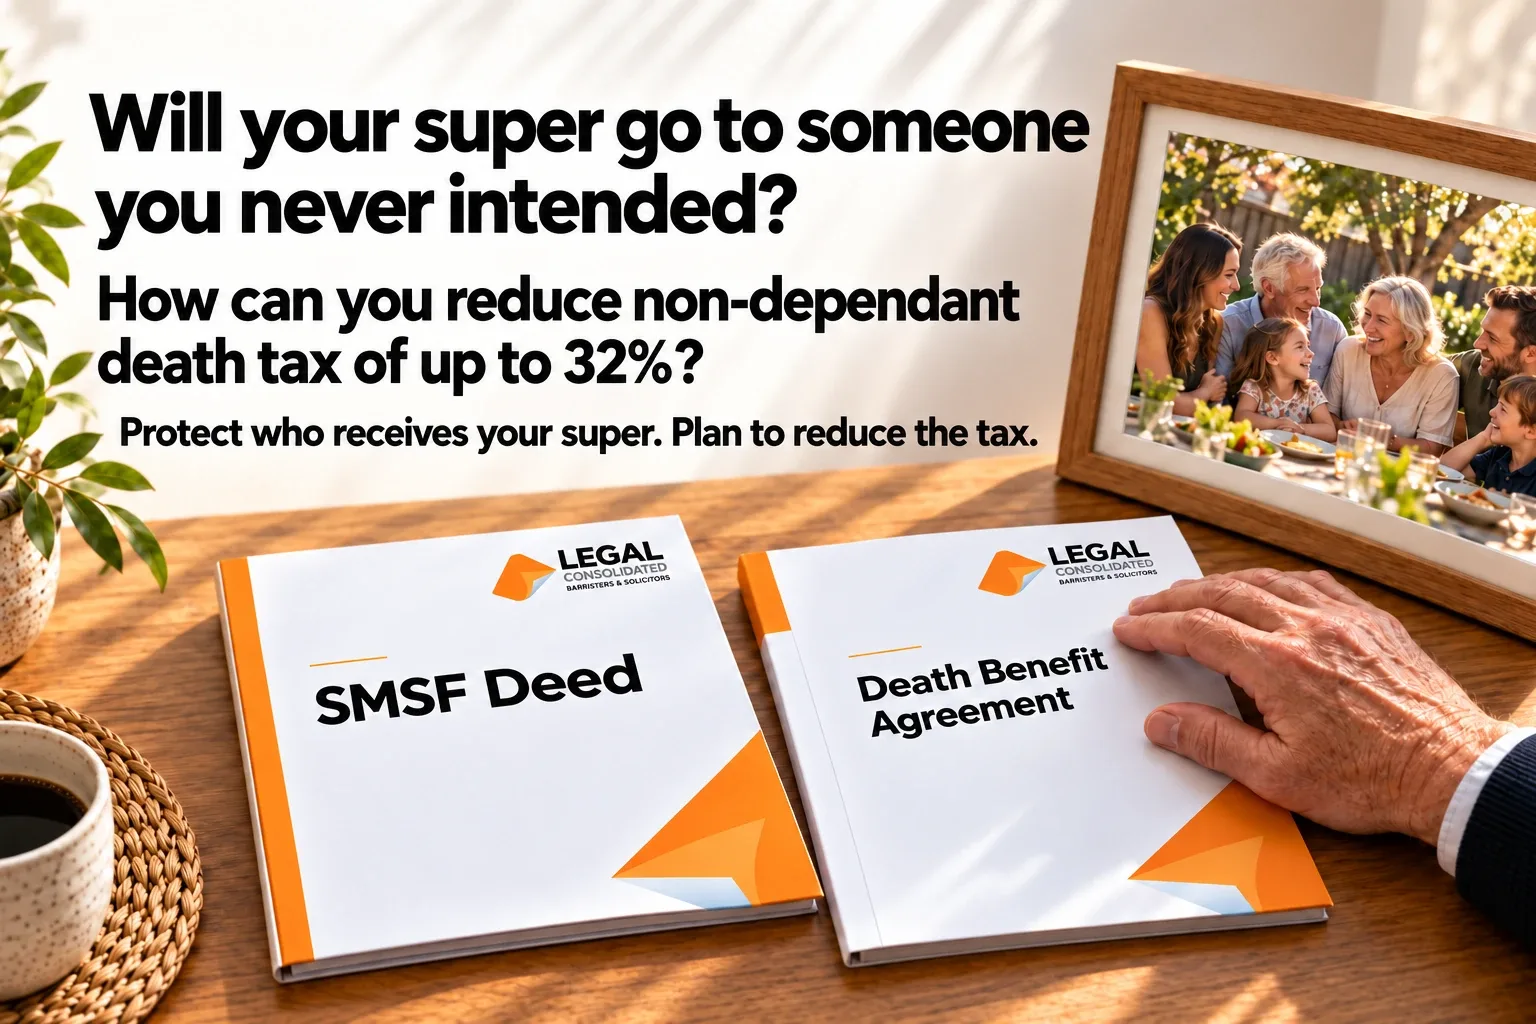
Who receives your super—and how they receive it—can change the tax outcome.
Your deed permits death benefits to be paid to eligible dependants or your legal personal representative. It also provides powers for death benefit pensions and reversionary pensions.
Use those powers with your accountant and financial planner to coordinate your super, pension arrangements and Will. Review who qualifies as a dependant for tax purposes, the taxable components of your super and whether benefits should be paid directly or through your estate.
Put the legal powers and signed directions in place while you can make those decisions. The deed supports the planning; the tax outcome depends on the strategy and circumstances.
Why does your SMSF hold these investments? What happens if one asset dominates the portfolio? Can the fund pay pensions, expenses and loan repayments?
Your investment strategy must address the fund’s circumstances, including:
These are matters addressed by reg 4.09 of the Superannuation Industry (Supervision) Regulations 1994 (Cth). The ATO expects a fund-specific strategy, rather than a repetition of the legislation or unexplained investment ranges. Read the ATO guidance.
The deed supplies broad investment powers. Complete your Investment Strategy and Diversification Strategy with your advisers so the written reasons reflect the investments your fund actually holds.
Give your accountant and auditor documented reasons for your investment approach.
The deed expressly provides powers for limited recourse borrowing arrangements, holding trusts, refinancing and acquiring legal ownership when the borrowing ends.
Those powers support borrowing arrangements structured to satisfy s 67A of the Superannuation Industry (Supervision) Act 1993 (Cth). The property purchase, loan and holding trust must also satisfy the applicable requirements. Read s 67A.
Your Bank Compliance Certificate identifies relevant deed powers for the lender’s assessment. Provide it with the complete signed deed when requested. Each lender decides what further information or advice it requires.
Your retirement arrangements may need to change as you reduce work, retire, receive an inheritance or lose a spouse.
The deed provides powers for account-based pensions, transition-to-retirement income streams and reversionary pensions. It also permits pensions to be stopped, commuted and restarted, subject to superannuation law.
Your accountant and financial planner can use those powers when implementing a pension, cash-flow or estate planning strategy.
A reversionary pension needs its own establishment arrangements. It is not created merely by signing the deed or completing a death benefit nomination.
Who will exercise trustee powers if a member loses capacity or dies?
The deed permits the appointment of qualifying legal personal representatives as trustees. This includes arrangements involving a member’s enduring power of attorney, subject to the statutory requirements.
Coordinate the deed with your enduring powers of attorney and, where the trustee is a company, its director succession arrangements. Complete the required appointments so the person you intend can legally act.
The deed also provides machinery for family law payment splits and benefit payments where a recipient cannot manage them.
Establishes the governing rules and trustee powers for investments, pensions, borrowing and death benefits.
Identifies Legal Consolidated’s legal work for the trustee client and explains signing and implementation.
Record the establishment decisions, adoption of the deed and relevant trustee and membership matters.
Explains members’ benefits, rights, risks and responsibilities.
Records the fund’s investment approach for completion and review with your advisers.
Records how the fund addresses diversification and investment concentration.
Identifies selected borrowing and banking powers in the deed for a lender’s review.
Keep the completed and signed documents together. They give you, your accountant and your auditor a consistent set of governing rules, decisions and supporting records.
Choose the fund’s name and proposed trustee structure with your advisers. Have the members’ details ready. If a company will be trustee, have its name and ACN beside you.
Use the checklist before you begin. A corporate trustee company is a separate purchase.
The educational building process is free. Read the hints and watch the training videos as you work through the questions.
You pay when you choose to buy the completed legal documents.
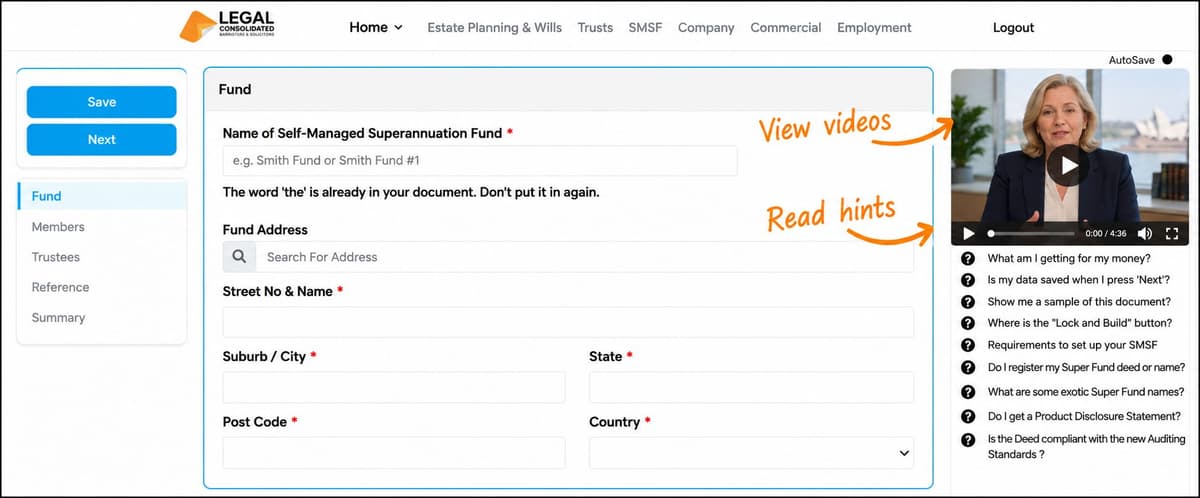
Review your answers, select Lock & Build, pay and download the documents.
Follow our law firm’s cover letter. Complete the required signatures and any separate death benefit directions. Keep the signed originals together.
Arrange the fund’s ABN, TFN and election for ATO regulation within the required period. Work with your accountant or registered tax agent on registration, bank accounts, contributions and rollovers.
Put the investment strategy and trustee records into practice. Review them as the fund’s circumstances change.
For help with the building questions, read the hints or telephone 1800 141 612.
The trustee holds and manages the fund’s assets for members’ retirement benefits. Choose the structure with your trusted advisers before completing the deed. The fund’s assets must remain separate from personal assets.
A Special Purpose SMSF Company gives the fund a continuing legal trustee. Changes to directors do not, by themselves, change the company that owns the assets as trustee. That reduces the title changes involved when human trustees join, leave or die.
The humans hold the fund’s assets as trustees. Changes to the trustees require attention to bank accounts, investment records and registered asset titles. Your deed and the ownership records need to tell the same story.
Legal Consolidated’s deed supports the chosen structure. Incorporating a company and making the necessary ASIC appointments are separate steps.
An SMSF has one to six members. For a fund with two or more members, the starting rule is that each member is a human trustee or a director of the corporate trustee, and each trustee or director is a member. The legislation provides specific exceptions.
A single-member fund with human trustees needs two trustees. A single-member fund with a corporate trustee has either the member as sole director or two directors meeting the statutory requirements. Unrelated members must not be in an employer–employee relationship. Trustee eligibility and relevant State trustee laws also need checking.
Complete the deed, validly appoint the trustees and set aside the initial trust assets for the members. A signed deed alone does not establish a fund with no assets. Follow the cover letter and the ATO establishment steps with your accountant.
Complete the ATO trustee declarations within 21 days of appointment. Directors of a corporate trustee must also meet the director ID requirements.
You or your registered tax agent apply for the fund’s ABN and TFN and elect for ATO regulation within 60 days after the fund is legally established. This is the application deadline. It is not a promise that the ATO finishes its checks within 60 days.
The fund has its own tax registrations. The corporate trustee has its own ACN and separate company obligations. An existing company’s other activities determine its own ABN and TFN requirements.
Read the deed and the death benefit agreement together. Select eligible recipients and specify their shares. Follow the form’s signing and witnessing instructions, including execution by the member and trustee. Give the completed original to the trustee and keep it with the fund records.
Signing the SMSF Deed alone does not complete the agreement. Check any existing nomination and reversionary pension arrangements before signing a new direction.
An Enduring Power of Attorney provides part of the succession machinery. Under the Superannuation Industry (Supervision) Act 1993 (Cth) s 17A(3)(b)(ii), a qualifying legal personal representative holding the member’s Enduring POA is permitted to be appointed trustee or director of the corporate trustee in the member’s place, subject to the statutory requirements.
The Enduring POA does not itself appoint the attorney as a director or authorise the attorney to perform the director’s office. Complete the separate trustee or company appointments. A Company Power of Attorney is a different instrument and does not replace those appointments. See ATO ruling SMSFR 2010/2.
Before a member moves overseas, review the fund’s residency, management and contribution arrangements with the accountant and financial planner. An attorney appointment alone does not settle every residency requirement.
Establish the fund on the right footing. Stamping depends on the jurisdiction and what the deed actually does. The following concerns a new SMSF deed establishing the fund with cash, without transferring dutiable property or declaring a new trust over it. Property purchases, contributions of land and borrowing holding trusts have separate requirements.
Where NT duty laws apply, lodge the deed and Stamp Duty Lodgement Form within 60 days after first execution. Nominal duty is $20, plus $5 for each duplicate or counterpart, where the deed is not otherwise chargeable with duty based on property value. Pay within that period unless the assessment specifies a later payment date. The NT rules cover deeds executed in the NT and deeds relating to NT property or a matter or thing done or to be done in the NT.
See Stamp Duty Act 1978 (NT) s 9, s 9B and sch 1 item 2. Postal address: Territory Revenue Office, GPO Box 1974, Darwin NT 0801.
An instrument establishing a complying SMSF, or a fund intended to become a complying superannuation fund, is covered by the superannuation exemption. It does not need Revenue NSW endorsement. See Duties Act 1997 (NSW) s 65(10)(a).
An instrument establishing the governing provisions of a complying superannuation fund is exempt. The exemption also covers a fund that, in the trustees’ opinion, will become complying within 12 months after execution. A deed satisfying those requirements does not require stamping merely because it establishes the fund’s rules. See Duties Act 2000 (Vic) s 39.
A trust established with cash only does not require stamping in Queensland. Cash contributions and cash benefit payments do not, by themselves, attract transfer duty. Transactions involving dutiable property require separate assessment. See Queensland Revenue Office guidance on trusts.
A new SMSF deed establishing the fund with cash, without a dutiable transaction, does not attract WA transfer duty or require stamping. RevenueWA distinguishes the fund deed from property acquisitions and declarations of trust, and requests stamped fund deeds and amendments where dated before 1 July 2008. See Duties Act 2008 (WA) ss 11 and 23 and RevenueWA’s superannuation guidance.
A deed establishing the fund with cash, with no transaction otherwise chargeable with duty, does not require duty assessment or lodgement merely because it is a deed. See Stamp Duties Act 1923 (SA) sch 2 pt 2, general exemption 30. Transfers of property and changes to beneficial interests require separate review.
A cash-only establishment deed, without a dutiable transaction, does not attract conveyance duty or require duty lodgement. See Duties Act 1999 (ACT) ch 2.
Superannuation trust deeds and variations dated on or after 1 July 2017 do not require stamping. Historical deeds dated before that date have different requirements. See State Revenue Office guidance, paragraph 1.3.
Keep the signed deed, trustee appointments, minutes, member records and later variations together. The auditor checks the fund’s financial statements and compliance; the deed supplies the governing rules against which decisions are assessed. A law firm-prepared deed supports that work. It does not replace the annual independent audit.
Our Supervising Partner, Adjunct Professor Dr Brett Davies, is honoured to have joined forces with well-known and award-winning authors Barbara Smith AM and Dr Ed Koken to produce the Self Managed Superannuation Fund Guide.
This practical, plain English guide is a valuable tool for everyone involved in SMSFs, including trustees, members, lawyers, accountants, and advisers. It is also tax-deductible when used to manage an SMSF.
You can buy your own copy directly from the publisher and keep it updated online here.
Self-managed superannuation funds are subject to specific Australian laws and regulations. The book provides detailed information on these rules, which include contributions, investments, taxation, compliance, and reporting requirements. Understanding these regulations is crucial to ensuring compliance and avoiding penalties.
Practical legal strategies from a national tax and superannuation law firm.
Join PRUDENCE