SMSF lending money? Protect your retirement savings with a Loan Agreement

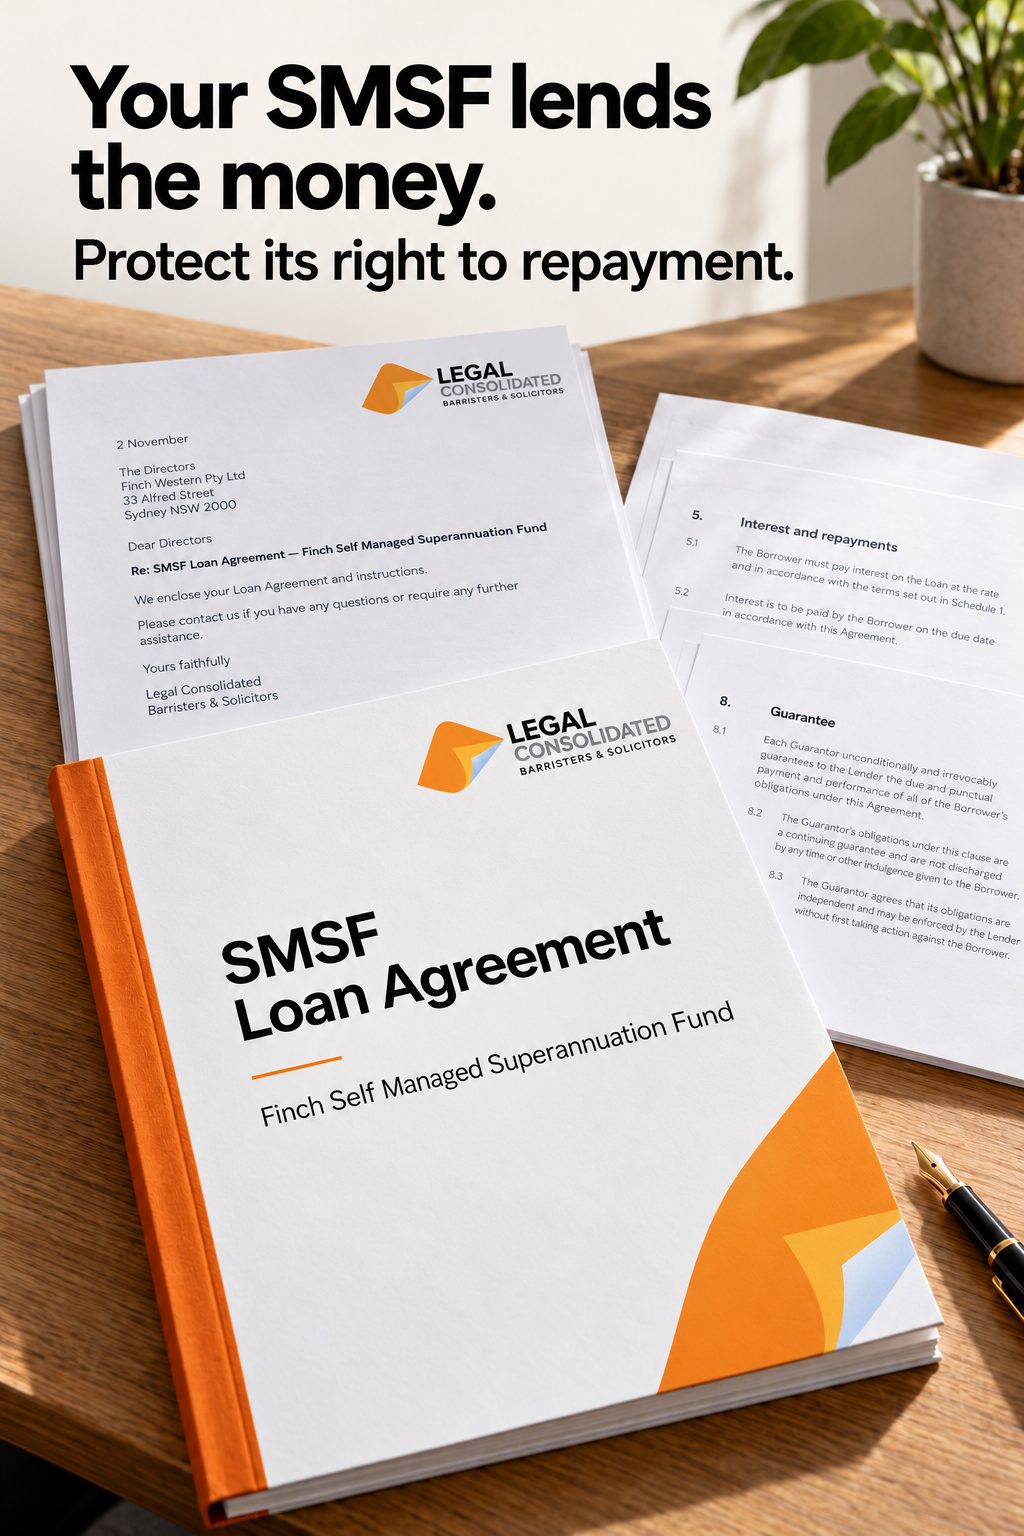
SMSF Loan Agreement for Finch Self Managed Superannuation Fund
  • SMSF Loan Agreement

  • $683 includes GST

Put your SMSF’s loan terms in writing before the money leaves its bank account.

Includes:

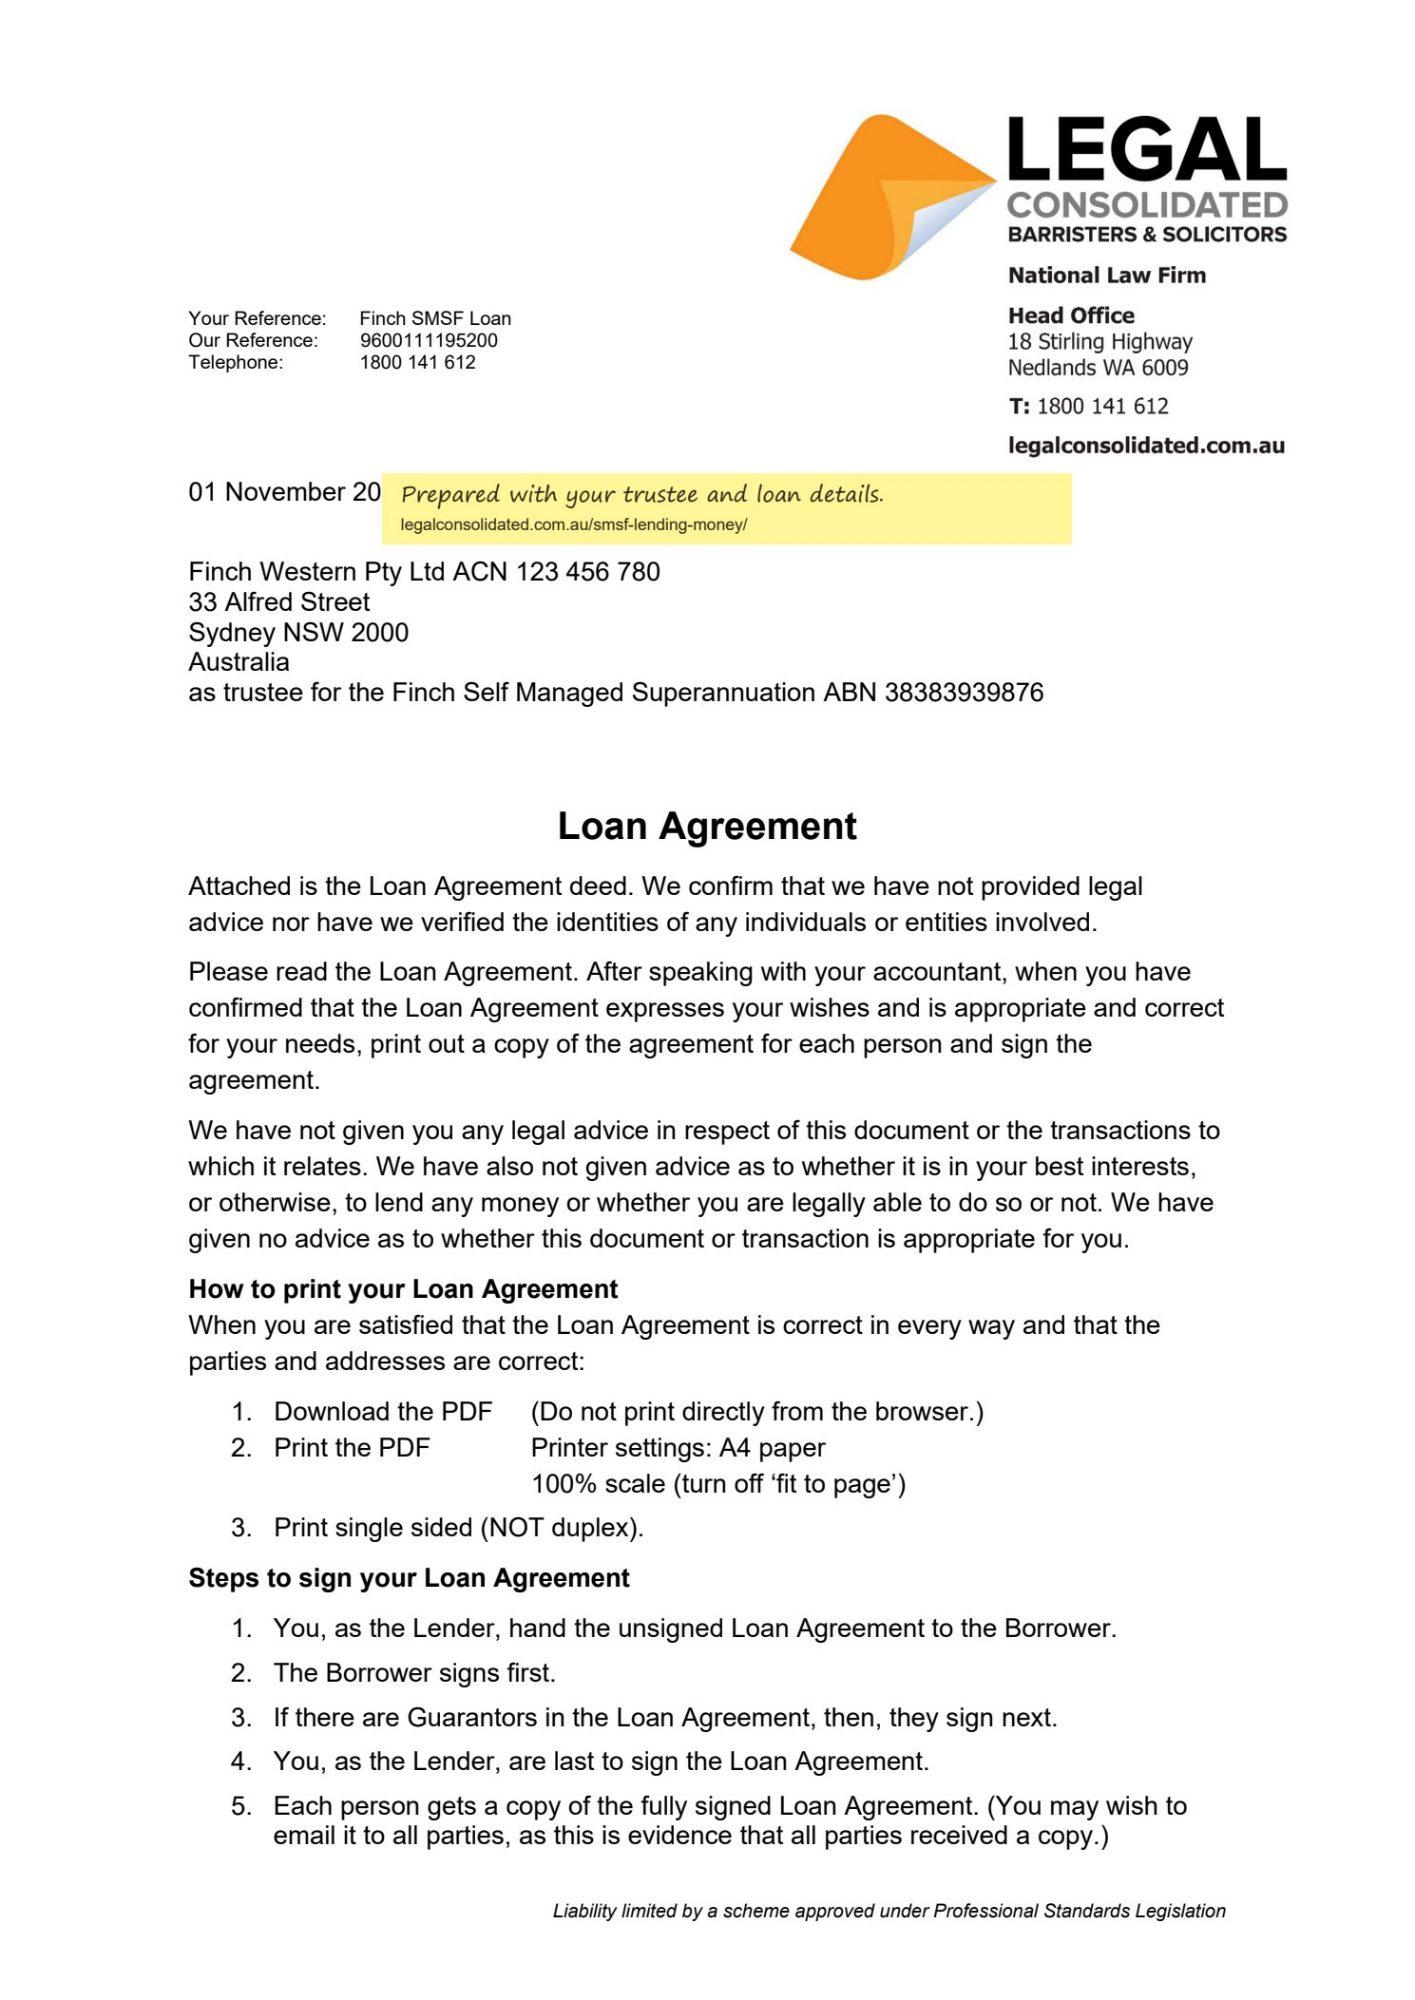
  • Legal Consolidated’s cover letter and instructions
  • Loan Agreement prepared from your answers
  • Your agreed interest and repayment terms
  • Guarantee provisions where you select guarantors

Your SMSF lends the money. How does it get the money back?

Your super is for your retirement. Lending money earns a return when the borrower pays the interest and repays the loan. But what happens when payments stop? Or the borrower disputes what you agreed?

Legal Consolidated’s Loan Agreement records who owes the money, the interest, when repayment falls due and the consequences of default. Put these protections in place before you transfer a single cent.

Build your SMSF Loan Agreement with the law firm that prepares it

More than 4,600 accountants, financial planners and lawyers build legal documents on Legal Consolidated’s website. You draw on our national law firm’s drafting and the guidance built into the questions.

We prepare your finished Loan Agreement from your answers and provide it with our law firm’s cover letter. You receive the document and instructions explaining its use. Read the hints as you build. Contact us for help answering the building questions.

Lock in your loan terms

Legal Consolidated’s Loan Agreement records:

  • The parties — identify the lender, borrower and any trustee capacity.
  • The loan amount — record the exact amount and arrangements for further advances.
  • Interest — record the agreed rate or method for setting it.
  • Repayment — set out when the borrower must repay, including repayment on demand where selected.
  • Default — establish contractual rights when the borrower fails to meet its obligations.
  • Guarantors — record their obligations if the borrower does not pay.

A loan to a company acting as trustee of a family trust needs the company and its trustee capacity properly identified. Your SMSF’s own trustee must also be correctly named. Our questions guide you through those details.

He called it a loan. The ATO challenged him.

Bruce Rowntree received substantial payments from companies he controlled. He said they were loans. The dispute exposed a serious problem: the absence of records showing an obligation to repay when the money changed hands.

In Rowntree v Commissioner of Taxation [2018] FCA 182, the Federal Court examined the evidence of the alleged loans. Believing that a payment was a loan did not establish the necessary agreement.

The lesson for your SMSF is practical. Record the repayment obligation when you make the loan. Keep the signed agreement and evidence of the money advanced. Do not leave your accountant to reconstruct the arrangement years later.

Legal Consolidated’s Loan Agreement gives you the document to settle and sign before advancing the money.

Your SMSF lent the money. Can you prove it was a loan? Rowntree v Commissioner of Taxation [2018] FCA 182

Who can your SMSF lend money to?

Unrelated companies or individuals

Yes. Lending is an investment your SMSF may undertake. The proposed loan must fit the fund’s investment strategy and comply with superannuation law. The ATO expects commercial, arm’s-length lending.

Consider the borrower’s ability to repay. What return does your SMSF receive for the risk? When does your fund need the money for pensions and expenses? Would an independent lender accept the proposed terms?

The sole purpose test in s 62 and the investment requirements in s 109 of the Superannuation Industry (Supervision) Act 1993 (Cth) underpin these decisions. Your Loan Agreement records the terms. Your accountant and financial adviser help you assess the proposed investment.

Your company or family trust

A related company or trust is different from a member personally borrowing the money. Some related-party loans are permitted, subject to the in-house asset rules and the other superannuation restrictions.

A loan to a related company or trust ordinarily counts towards the fund’s in-house assets. The 5% limit applies to the fund’s total in-house assets, not a separate allowance for each loan.

For example, a fund with assets worth $2 million has a $100,000 in-house asset limit. Existing in-house assets use part of that allowance. Staying below the limit does not, by itself, make a proposed loan lawful. Have your accountant check the arrangement before the money moves. Then record the agreed terms in your Legal Consolidated Loan Agreement.

You or your relatives

No. Section 65 of the Superannuation Industry (Supervision) Act 1993 (Cth) prohibits lending fund money to members or their relatives. It also prohibits other financial assistance to them using fund resources.

The 5% in-house asset limit does not override that prohibition. Routing money through a company does not cure an arrangement that provides prohibited financial assistance.

A Loan Agreement to make even your auditor smile

Your auditor asks about money that has left the fund. You produce the signed Loan Agreement, bank records and repayment history. The interest calculation matches the agreement. The outstanding balance matches the accounts.

That is a clearer story than “we agreed to sort it out later”.

Legal Consolidated’s Loan Agreement puts the contractual terms in one place. Keep it with the records showing how you assessed the loan and how the borrower performs. The document and the conduct should tell the same story.

SMSF Loan Agreement for Wattle Retirement Superannuation Fund with a smiling ATO Auditor

Protect your SMSF when repayments stop

The borrower misses a payment. You need to know what is due, what amounts to default and what your agreement permits you to do next.

Your Legal Consolidated Loan Agreement sets out the borrower’s obligations and your contractual rights when the borrower defaults. A guarantee adds another person’s promise to meet the obligations covered by that guarantee. Each guarantor should obtain independent legal advice before signing.

Security is a separate consideration. If you want additional protection over assets, arrange the appropriate security documents and any registration needed to make that protection effective. Signing a Loan Agreement does not itself register a mortgage or a security interest.

Check three things before your SMSF advances the money

  1. Your SMSF Deed. Check its lending powers. Update your SMSF Deed where required.
  2. Your Investment Strategy. Record why the loan fits your fund’s objectives, risks and cash needs. Build your Investment Strategy and supporting Statement Library.
  3. Your Loan Agreement. Settle the terms and obtain the required signatures before advancing the money.

Build your SMSF Loan Agreement with help at each step

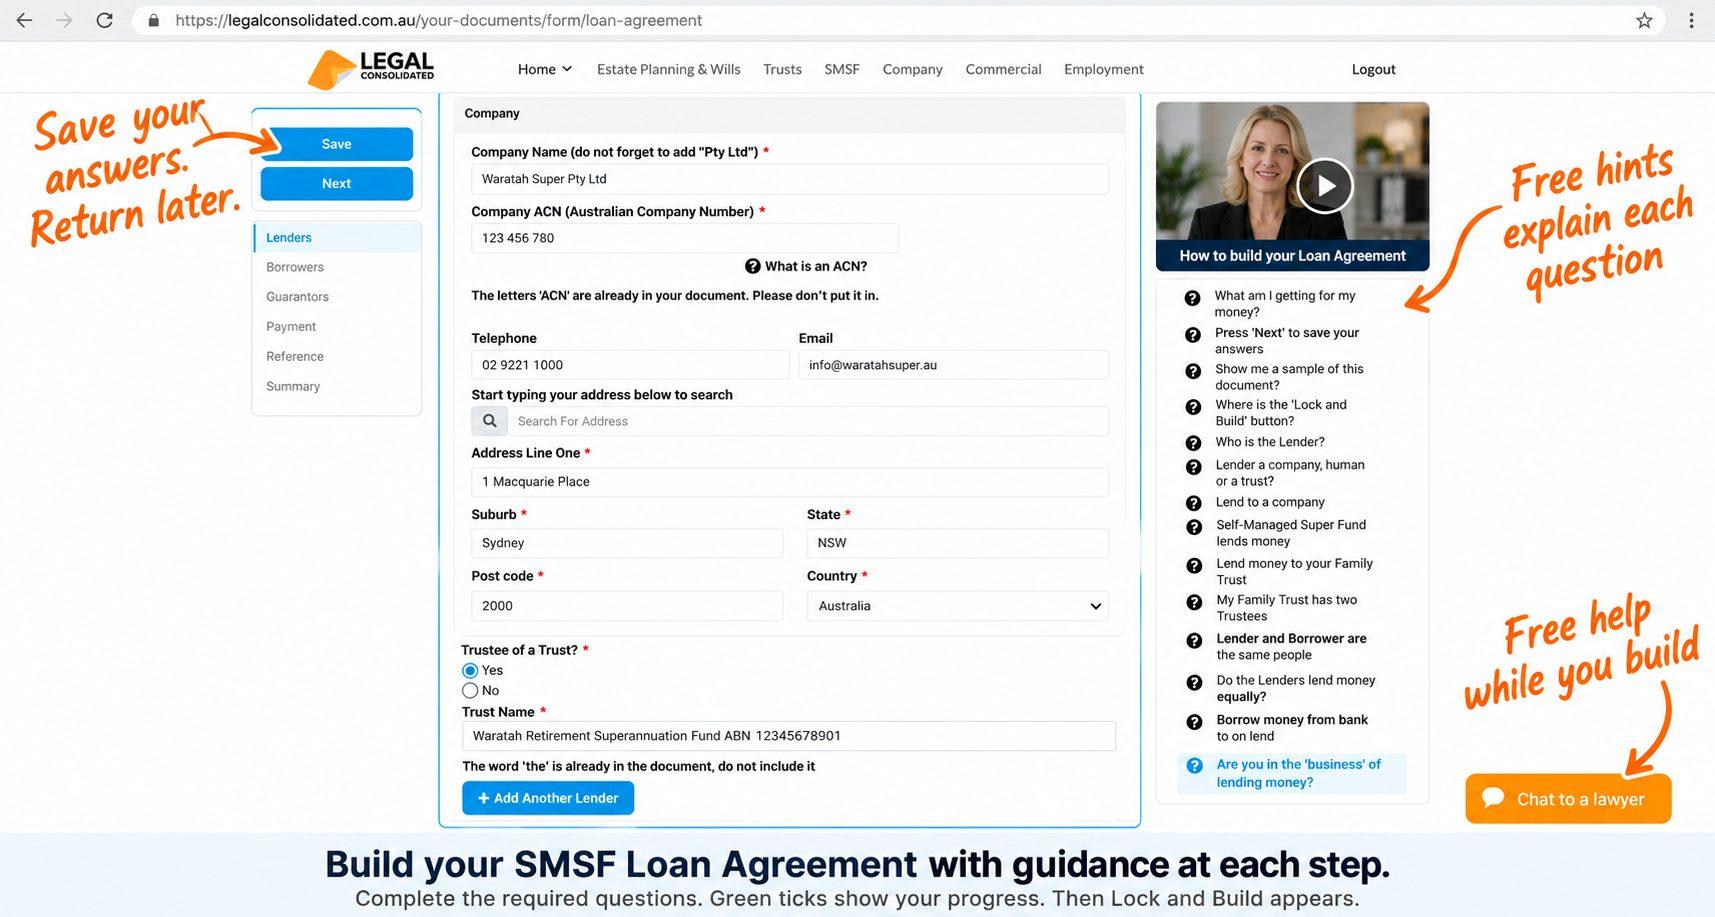
Start for free. Answer the questions about your lender, borrower, loan terms and guarantors. Read the hints beside the questions. Save your answers and return later.

Once the required sections show green ticks, the Lock and Build option appears. You also have access to help while you build. Telephone, email or use “Chat to a lawyer” for assistance with the building questions.

START BUILDING FOR FREE

Build your SMSF Loan Agreement with free hints, videos and help at each step