Your business-running spouse needs money. Protect your right to repayment with a Loan Deed.
Your husband or wife needs money for a business, an investment or an expense.
Your spouse runs a business, is a director, or provides professional services. You want to help. You also want your at-risk spouse to repay the money.
Legal Consolidated’s Spouse Loan Agreement records the debt, your repayment terms and what happens if the borrower defaults. Sign before transferring the money. Keep your family's wealth protected.
The man of straw and woman of substance — Spouse Loan Agreement for asset protection
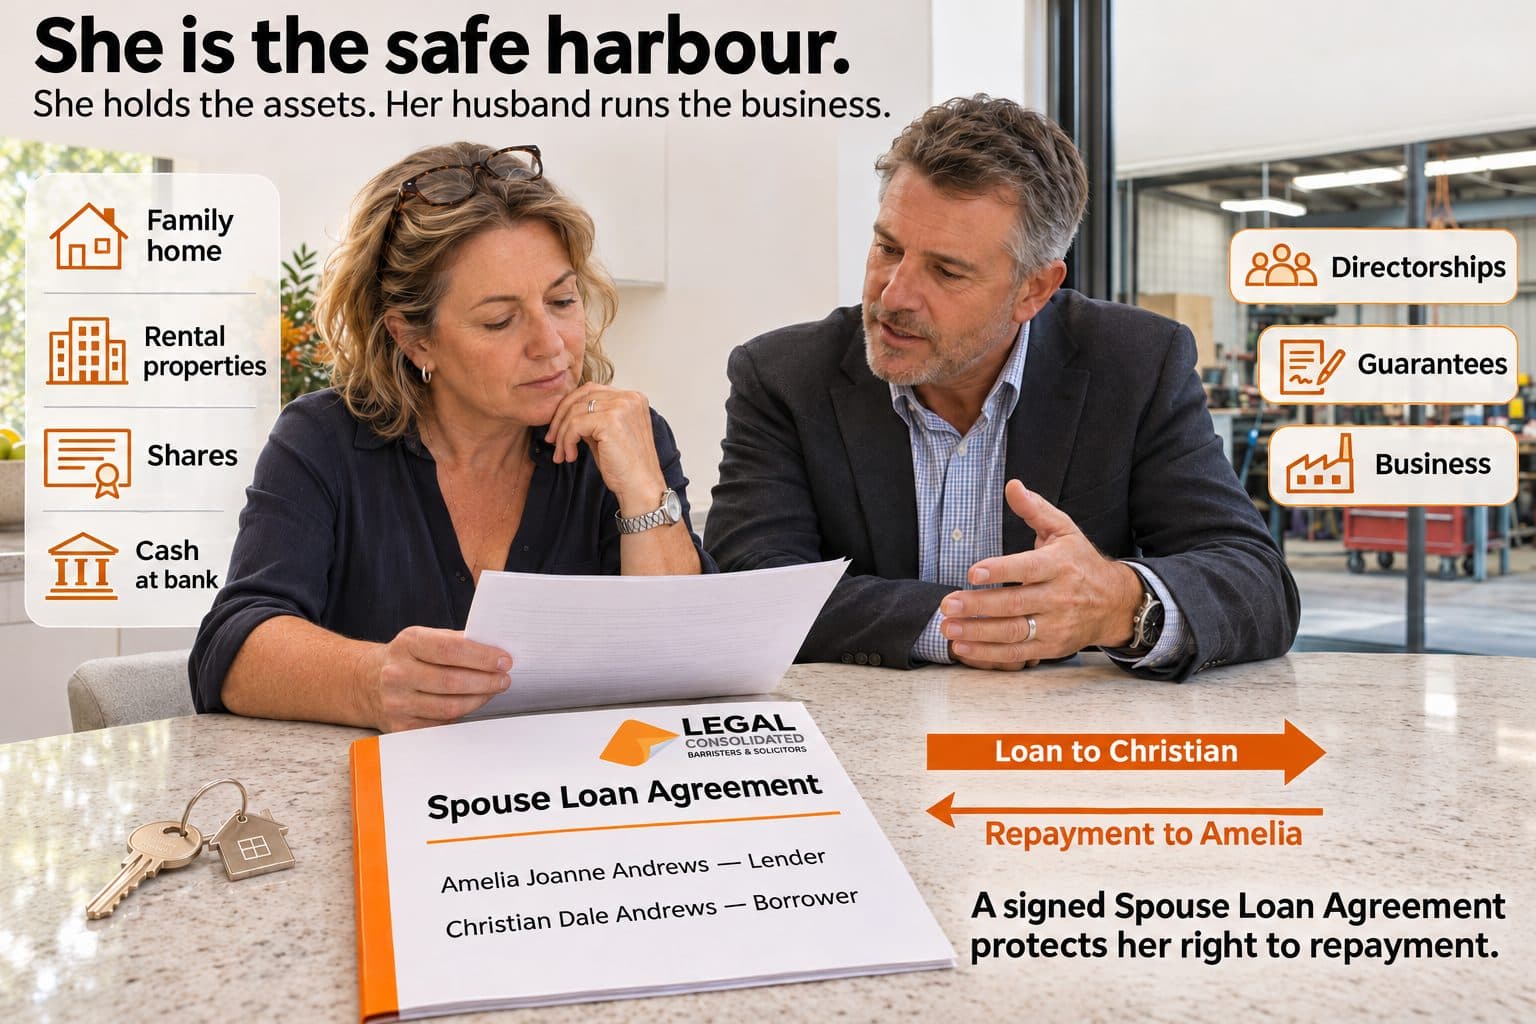
One spouse runs the business or practises a profession. That spouse faces claims from clients, suppliers and creditors. The other spouse holds the family wealth.
What happens when the spouse holding the savings lends money to the spouse running the business?
Wife lends money to her business husband — protect the family savings
Emma holds $200,000 in her own bank account. Daniel runs a business. He needs the money, but Emma wants to keep her right to repayment.
Emma does not give Daniel the money. She lends it to him. Their Legal Consolidated Spouse Loan Agreement names Emma as lender and Daniel as borrower. It records the advance, interest arrangements and repayment obligations.
Emma exchanges cash for a contractual right to repayment. Daniel owes her the money. They keep the signed agreement and bank records together and follow the agreed terms.
If Daniel’s company borrows instead, name the company as borrower. Select a personal guarantee if Daniel also promises to repay the company’s debt.
Safe harbour Family Trust — separate family investments from business risks
Your business needs working capital. Your family also needs somewhere to hold its investments.
Who controls the Family Trust when you die or lose capacity? Review its Appointor, backup Appointors and trustee through our Family Trust Update. The structure holding your wealth and the documents controlling it need to work together.
Choosing the trustee? Read about a company as trustee of your Family Trust. Keep the trustee’s role distinct from the company borrowing money or operating the business.
Personal guarantees expose the safe harbour spouse’s assets
Daniel’s bank asks Emma to guarantee his business overdraft. Emma holds the family assets. Her guarantee exposes those assets to the bank if Daniel’s business fails.
Your Spouse Loan Agreement records money owed to you. A guarantee may make you responsible for money owed by someone else.
Spouse loans and bankruptcy — sign before advancing the money
Prepare and sign the agreement before advancing the money. Record each advance and repayment. Your documents and bank records should tell the same story.
A genuine loan supports your position as a creditor. It does not guarantee recovery or override bankruptcy law. Transfers for less than value and transfers intended to defeat creditors face challenge under s 120 and s 121 of the Bankruptcy Act 1966 (Cth).
Protecting the family home from an ATO claim — Bosanac v Commissioner of Taxation
In Bosanac v Commissioner of Taxation[2022] HCA 34, a husband and wife used joint borrowing to buy a home in the wife’s name. The Commissioner sought a declaration that the husband held a beneficial interest in it to assist recovery of his tax debt.
The High Court allowed the wife’s appeal. The evidence supported the conclusion that she owned the home beneficially. The Court examined what the couple intended, including their history of holding assets separately.
The lesson for your family is to make your intention clear when the money moves. Do you intend a gift, a loan or shared ownership? Your Legal Consolidated Spouse Loan Agreement records a loan and the obligation to repay. It does not leave that question to assumptions about your marriage.
Proving a family loan — Rowntree v Commissioner of Taxation
In Rowntree v Commissioner of Taxation[2018] FCA 182, an experienced lawyer said payments from companies he controlled were loans. He lacked records made at the time to support much of the arrangement. His appeal failed.
This was a tax case about company payments, but the practical lesson matters when you lend to your spouse. Believing you have made a loan is different from proving its terms. Have the agreement prepared and signed before the advance. Keep the evidence of payment and repayment with it.
More than 4,600 accountants, financial planners and lawyers build legal documents on our website. Legal Consolidated prepares your finished Loan Agreement from your answers and provides it with our law firm’s cover letter and instructions.
Spouse Loan Agreement — choose your interest and repayment terms
When do you want the money back? You might agree on instalments, a fixed repayment date or repayment on demand. Record the arrangement you actually intend to follow. Select the interest terms that match your agreement.
Your Legal Consolidated Loan Agreement brings the amount, interest, repayment and default provisions together. It also includes guarantee provisions where you select guarantors. A guarantor must obtain advice from their own independent lawyer.
If you want additional protection over property or other assets, arrange the appropriate security documents and any registration needed. Signing the Loan Agreement does not itself register a mortgage or security interest.
Spouse Loan Agreement for family asset protection in bankruptcy
Your spouse dies — does your Spouse Loan Agreement continue?
The debt does not disappear simply because one of you dies. If the borrower dies, the lender claims repayment from the borrower’s estate. If the lender dies, the debt forms part of the lender’s estate.
Legal Consolidated’s Loan Agreement addresses executors and legal personal representatives. Keep the original agreement and repayment records for the person administering the estate. Coordinate the loan with your Will and estate planning. Do not assume that leaving everything to your spouse automatically cancels the debt.
Spouse Loan Agreements and Family Court property settlements
You may agree today about the loan and disagree years later. A signed agreement records what each of you promised. Bank records, repayments and correspondence help show that you treated the arrangement as a real loan.
A Spouse Loan Agreement is different from a financial agreement dividing property on separation. The Family Court retains its powers over property and debts. Your loan documents give your advisers evidence of the arrangement; they do not dictate the outcome of a property settlement.
Already lent the money? Recognition of Loan Deed
Tell your adviser when the money moved and what you agreed at the time. Keep the bank records, emails and messages. Do not backdate a document or describe a gift as a loan after the event.
If you need to document an existing loan, consider our Recognition of Loan Deed. Start with the true history so your adviser can identify the appropriate document.
Family asset protection — connect your Spouse Loan Agreement, trusts and Will
Your Spouse Loan Agreement forms part of your family’s wider plan. Connect the loan with the structures holding your wealth, your Will and your superannuation arrangements. Review the plan when your family, assets or business changes.
Reversionary Pension Kit — discuss continuing your pension to an eligible dependant with your financial planner and accountant.
Before moving property or changing ownership, ask your accountant and lawyer to assess Capital Gains Tax and stamp duty. Coordinate the documents before the transaction.
Build your Spouse Loan Agreement with help at each step
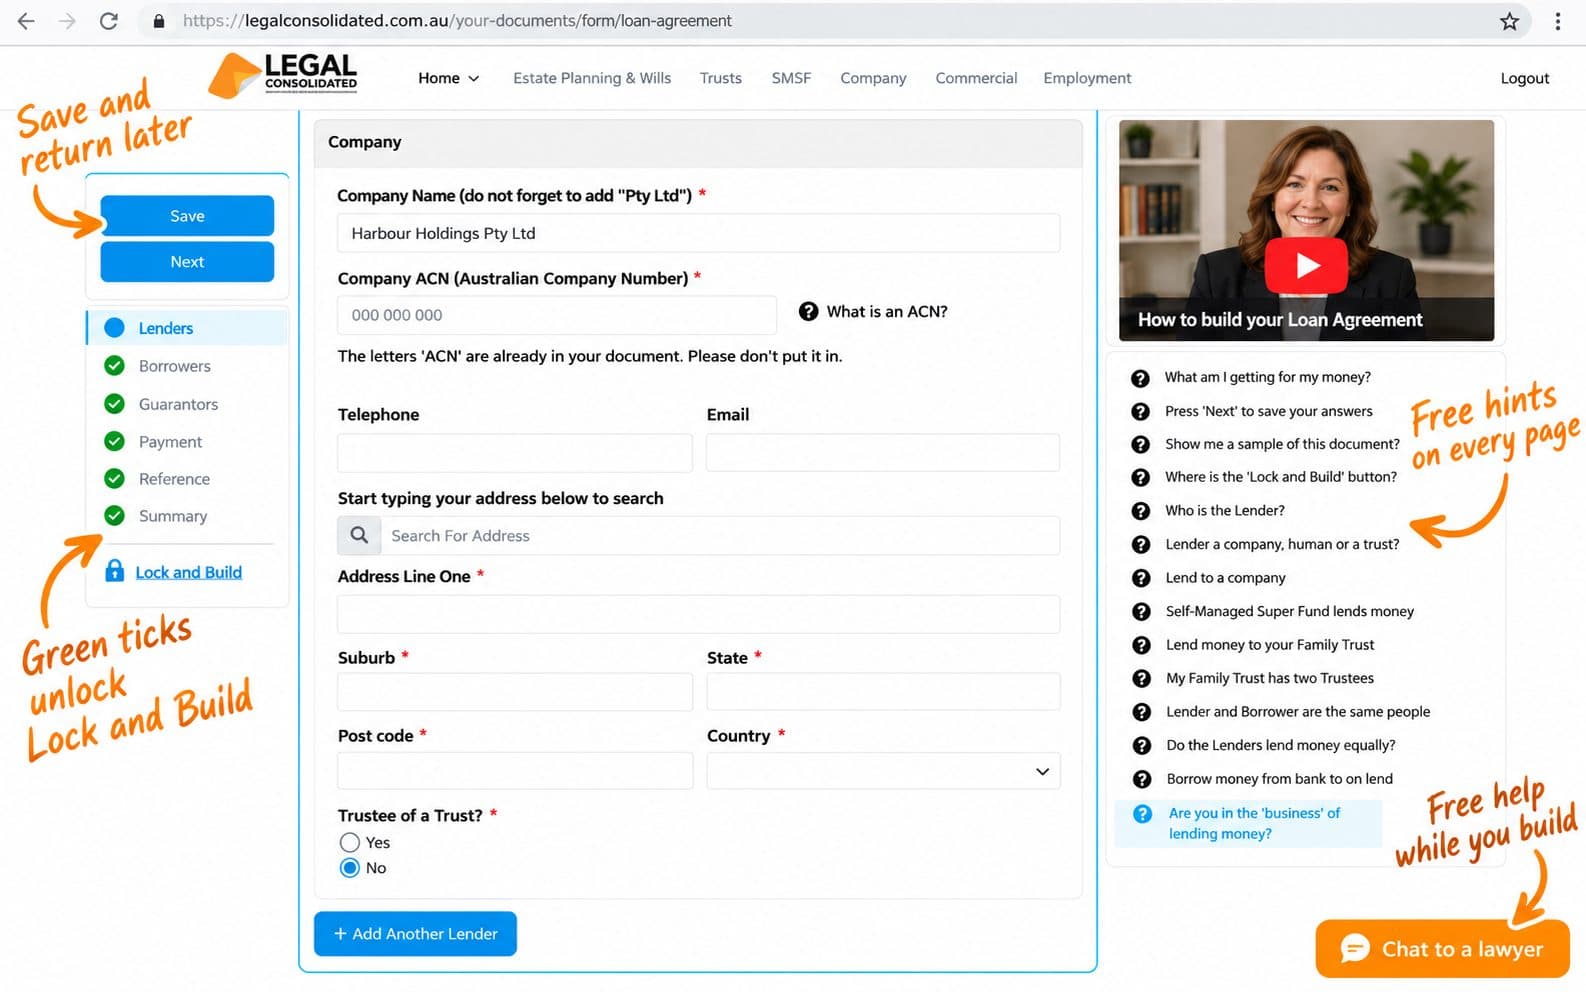
Start for free. Answer the questions about the lender, borrower, loan terms and guarantors. Read the free hints beside the questions. Save your answers and return later.
Once the required sections show green ticks, Lock and Build appears. Telephone, email or use Chat to a lawyer for help answering the building questions. Check the Summary, complete your instructions and receive your documents. Sign before advancing the money.
If you intend a gift, use a Deed of Gift. Keep a gift and a loan distinct from the outset.
Giving money away or forgiving a family loan?
A Deed of Gift documents an intended gift. A Deed of Debt Forgiveness deals with releasing an existing debt. Discuss the tax and asset protection consequences before giving up your right to repayment.