Loan to Parents — pay for their aged care. Protect your money.

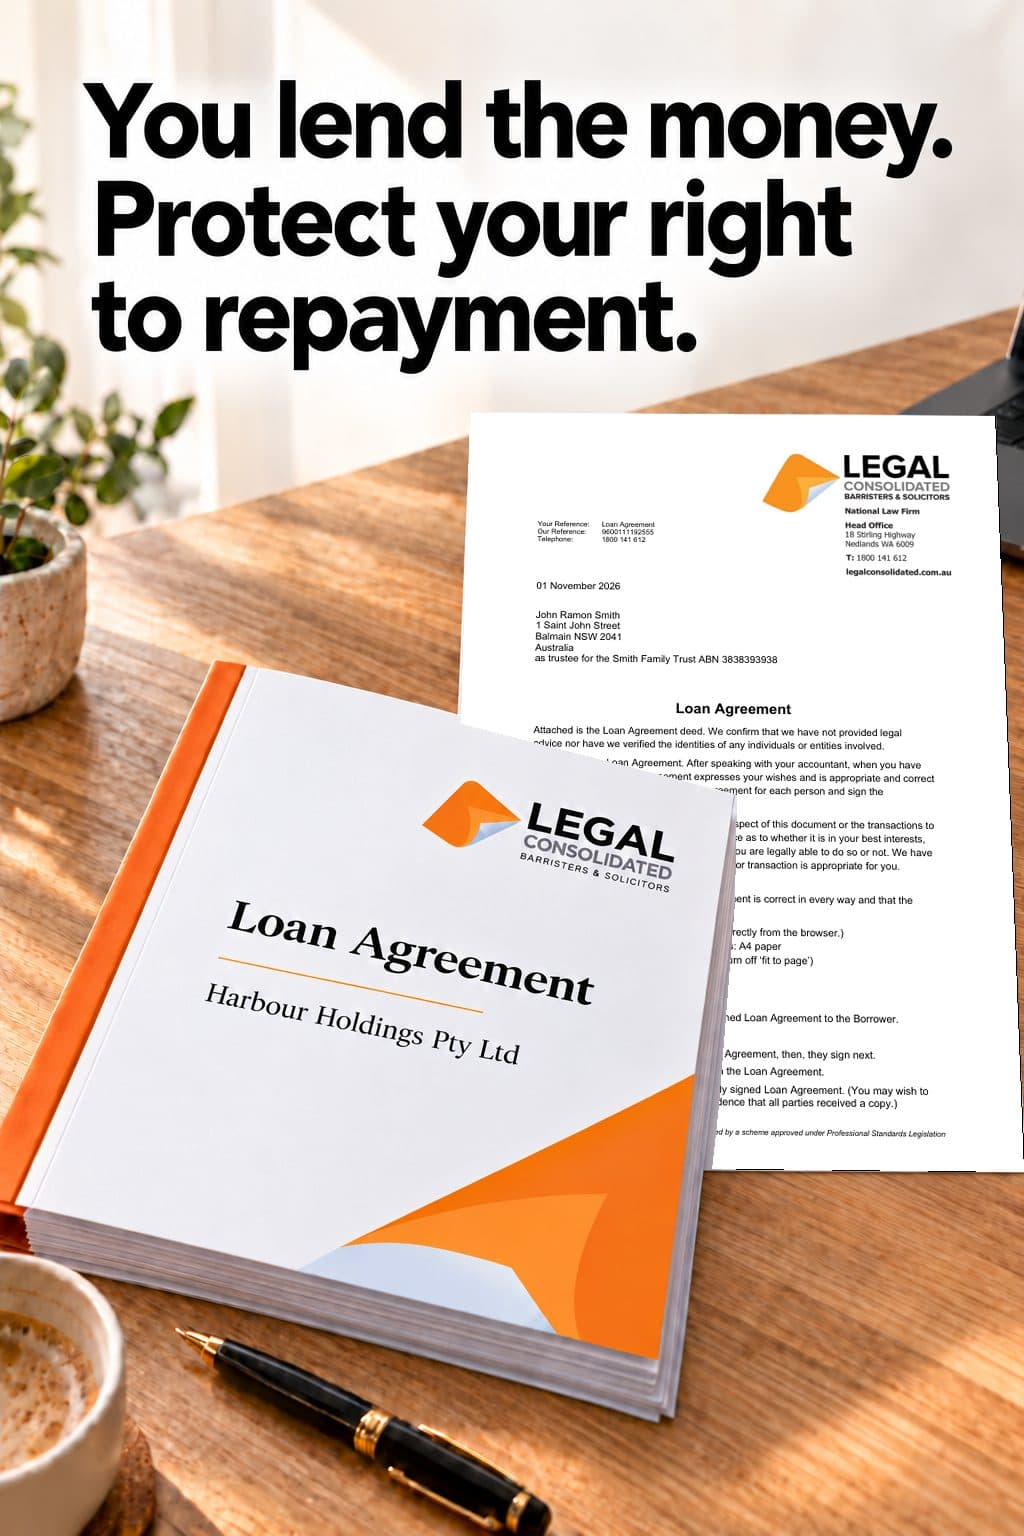
Loan Agreement book cover
  • Loan to Parent Agreement

  • $683 includes GST

Help your parents get the care they need. Keep your right to repayment.

Includes:

  • Law firm’s cover letter and instructions
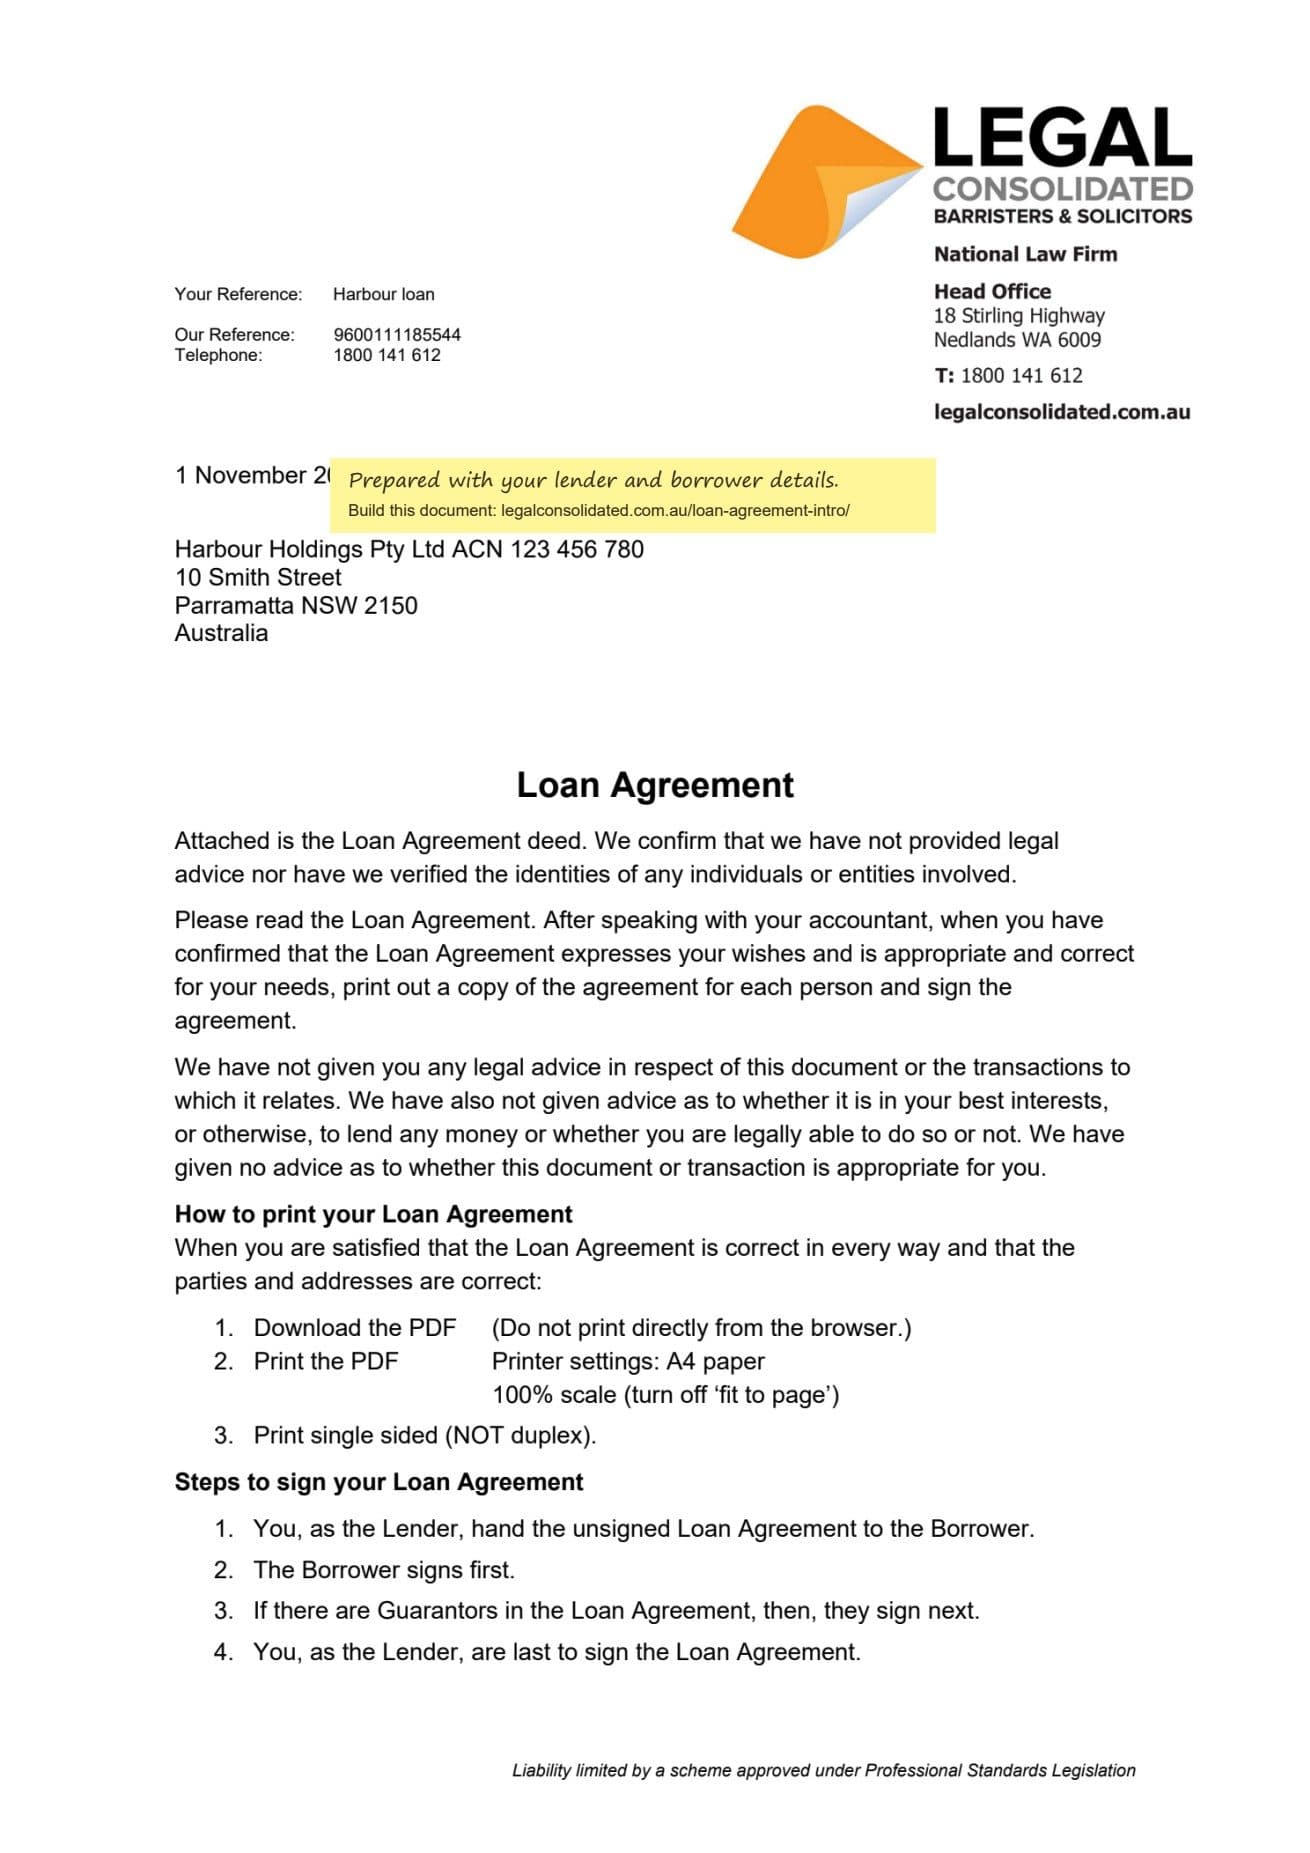
  • Loan Agreement prepared from your answers
  • Your selected interest and repayment terms
  • Multiple lenders and guarantee provisions where selected

You pay for Mum’s aged care. Your siblings call it a gift.

Mum needs a good nursing home. Her wealth sits in the family home. Your financial planner and accountant recommend keeping the home, but Mum needs money for her aged care accommodation.

You have worked hard. You have the money. You lend Mum $500,000 so she gets the care she needs.

Years later, Mum dies. Your siblings want to divide her estate. You ask for your $500,000 back.

“What loan?” they ask. “You gave Mum that money.”

Help your parents. Keep your right to repayment. Legal Consolidated prepares your Loan to Parent Agreement. Your parent signs before you advance the money. The agreement records a debt that you claim from their estate. You give the executor evidence of what your parent owes you, instead of leaving your siblings to rewrite the arrangement.

You pay Mum’s nursing home deposit. Who gets the refund when she dies?

An aged care home may offer a lump-sum accommodation payment called a Refundable Accommodation Deposit (RAD). You lend Mum the money to pay it.

When Mum dies, the remaining deposit balance forms part of her estate. Paying the deposit does not automatically give you the right to collect that refund yourself.

Your Legal Consolidated Loan to Parent Agreement records Mum’s debt to you. Keep the signed agreement, bank transfers and aged care receipts together. Give the executor the evidence to deal with your loan before distributing the remaining estate.

The aged care refund and your loan are separate amounts. Permitted deductions may reduce the refund. A smaller refund does not, by itself, reduce the debt recorded in your agreement. Read the government’s explanation of accommodation refunds.

Keep the family home. Document the money you lend your parents.

Dad owns the family home but has little cash. He needs aged care. You have enough money to help him move without forcing an immediate sale of the home.

Your accountant and financial planner assess whether keeping the home makes sense. They consider the care costs, rent, tax and Centrelink treatment. Legal Consolidated prepares the Loan to Parent Agreement recording the money you lend.

Do not assume that retaining the home or calling the payment a loan produces a particular pension or aged care fee result. Work through those figures with your advisers. Our Centrelink and family loan guidance explains why the documents and the facts must tell the same story.

If you want security over the home, discuss a mortgage or other appropriate security with your property lawyer. The signed Loan Agreement does not itself register security or give you priority over secured creditors.

Your siblings say it was a gift. Produce your Loan to Parent Agreement.

Your brother did not contribute to Mum’s care. Your sister did not contribute either. But Mum’s Will divides her estate equally among all three of you.

That does not turn a genuine debt into an inheritance to share. Your claim as lender and your entitlement under the Will do different jobs.

Legal Consolidated’s Loan to Parent Agreement puts the repayment obligation in writing. Your bank records show the money you advanced. The executor has evidence to assess the debt instead of relying on conflicting memories.

Tell the executor about the loan promptly. A signed agreement supports your claim; the estate still needs enough assets to meet its debts.

You pay the aged care home directly. Mum still needs to acknowledge the loan.

Mum asks you to send the money straight to her aged care provider. The money never passes through her bank account.

Record that payment as an advance made for Mum at her direction under the Loan Agreement. Keep her instructions, the provider’s invoice and the receipt with the agreement.

The provider’s receipt proves you paid the provider. Your Loan to Parent Agreement records why Mum owes you the money. Get the agreement signed before making the payment.

Two children contribute different amounts. Record each child’s loan.

You lend Dad $400,000. Your sister lends him $100,000. Your brother contributes nothing.

Record who lends each amount. Do not leave the executor guessing whether you each supplied half, or whether one child gave the money away.

Identify the lenders and borrower correctly when building the Loan Agreement. Keep a separate record of each person’s advances and repayments. Where you make separate loans on different terms, use separate agreements.

Dad may need further help with ongoing fees. Record each further advance covered by the agreement so the outstanding balance stays clear.

Mum loses capacity. Do not leave the Loan Agreement until later.

Mum agrees to borrow today. Months later, illness stops her understanding and signing the documents. Your siblings then question what she agreed.

Prepare and sign the Loan Agreement while Mum understands the arrangement. Do not wait until a crisis or backdate an agreement.

If an attorney needs to sign for your parent, check the Power of Attorney and the attorney’s authority first. If you are both the lender and your parent’s attorney, obtain advice about that conflict before proceeding.

A sibling’s approval does not replace your parent’s valid agreement or an attorney’s legal authority.

Your parent’s Will and your Loan Agreement do different jobs.

Mum’s Will says who receives what remains of her estate. Your Loan to Parent Agreement records what she owes you.

Do not rely only on a promise that Mum will “sort it out in her Will”. She may change her Will. The estate may face competing claims. Keep the debt properly documented throughout her life.

Coordinate the loan with your parents’ Wills and estate planning. Keep a current loan balance and tell the executor where to find the signed agreement.

If you later choose to release the debt, consider a Deed of Debt Forgiveness. If you intend a gift from the outset, use a Deed of Gift. Keep those decisions distinct.

Family loan evidence — Rowntree v Commissioner of Taxation

In Rowntree v Commissioner of Taxation [2018] FCA 182, an experienced lawyer argued that payments from companies he controlled were loans. He lacked records made at the time to support much of the arrangement. His appeal failed.

This was a company-tax case, not an aged care dispute. The practical lesson is clear: believing money is a loan does not prove the agreement.

Legal Consolidated prepares your finished Loan Agreement from your answers and provides our law firm’s cover letter and instructions. Sign before advancing the money. Keep the records showing what happened.

Already paid for your parents’ aged care? Review the existing loan.

Find the bank transfers, emails, invoices and messages showing what you agreed when you paid. Do not describe a gift as a loan after a dispute starts.

Consider our Recognition of Loan Deed when documenting an existing debt. Your lawyer needs the true history and must check any time limits for enforcing it.

Start with the evidence you already have. Do not backdate the documents.

Build your Loan to Parent Agreement with Legal Consolidated

More than 4,600 accountants, financial planners and lawyers build legal documents on our website.

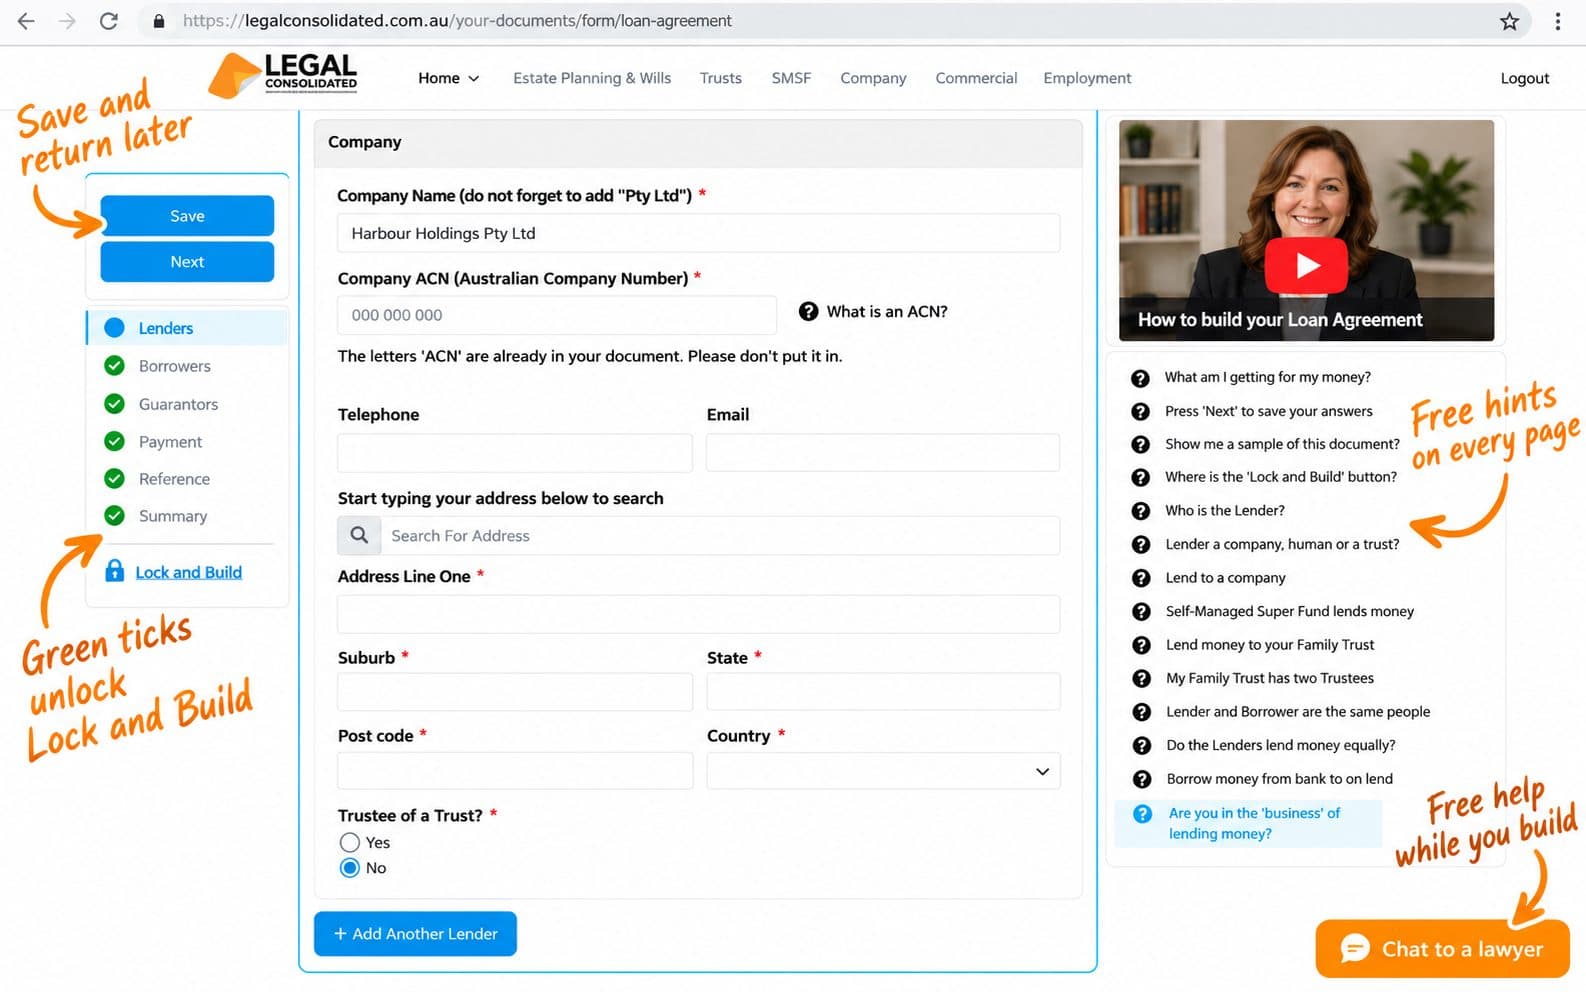
Start for free. Answer the questions about the lender, parent borrowing the money, loan amount, interest and repayment terms. Read the hints and watch the videos. Save your answers and return later.

Telephone, email or use Chat to a lawyer for help answering the building questions. Once the required sections show green ticks, Lock and Build appears.

Help your parents get the care they need. Protect your right to repayment before you hand over the money.

START BUILDING FOR FREE

Build your Loan to Parent Agreement with free hints, videos and help

Free Loan to Parents and family asset protection resources